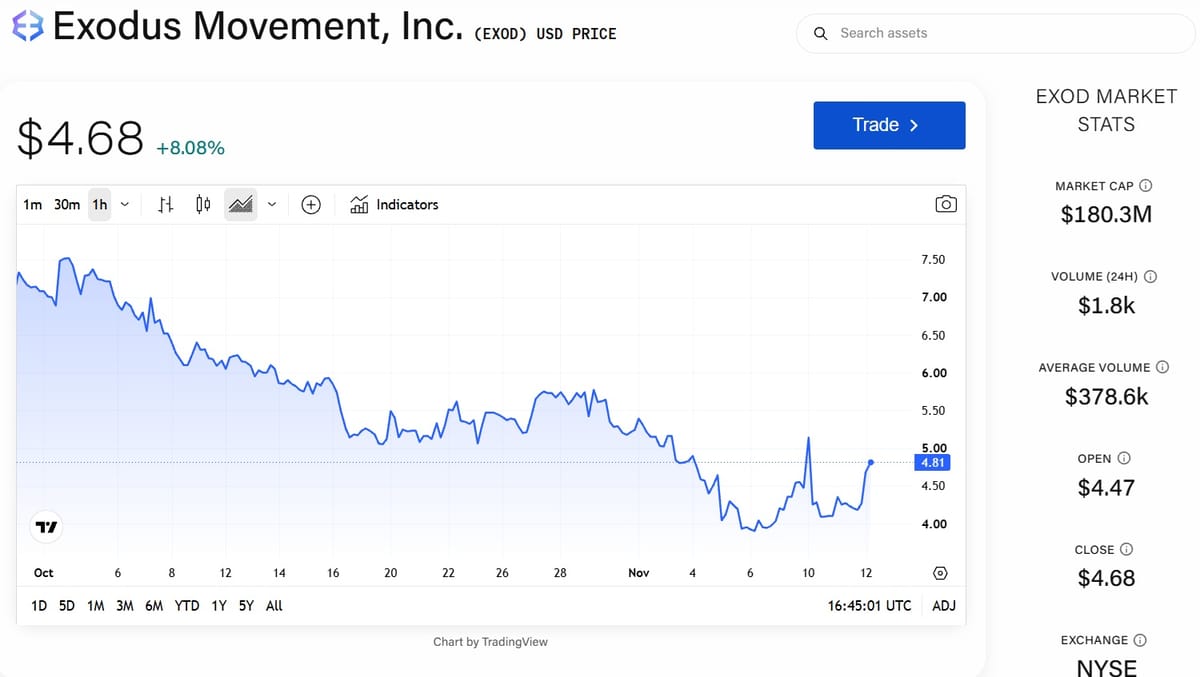
In a report published November 12, 2026, at 16:54 UTC, Exodus Movement (EXOD) shares were reported up more than 8% to $4.68 that Thursday morning. StoneX maintained its Buy rating and $12 price target, which implied roughly 150% upside from that morning’s share price. The target is StoneX’s assessment, not a forecast of a certain return.
StoneX analyst Mark Palmer wrote that Exodus’s shift into payments and its lower cost base were helping offset weaker activity in its crypto wallet business. “The cost reset is real,” he said.
Exodus reported third-quarter revenue of $32.5 million on Monday, November 9, above analyst estimates of $29 million to $31 million. Its adjusted EBITDA loss narrowed to $3.9 million from $6.7 million in the second quarter, while its net loss was $8.3 million.
Payments brought in nearly $11 million in their first full quarter after Exodus acquired Monavate and Baanx in May. That helped offset a 29% year-over-year decline in wallet-related revenue to $21.6 million. Exodus said traditional payments accounted for about 64% of payments revenue, with onchain finance making up the remaining 36%.
The company reduced headcount from 326 to 214 between May and Monday’s earnings report. Management expected roughly $30 million in annual savings going into 2027. CEO JP Richardson said on the earnings call that higher exchange volumes could lift revenue without a proportionate increase in overhead. He also cautioned that several company milestones still depended on regulatory approval and execution. Exodus was awaiting approval in Latvia to resume issuing payment cards in Europe; it said card issuance had already resumed in the U.S.