ChainCatcher published this accounting on November 10, 2026. It covers the third quarter of 2026, and it dates Bitcoin’s move from about $58,600 in early July to about $83,600 in early October — a gain of about 43%. Over that window, the primary market did not warm up with the coin.
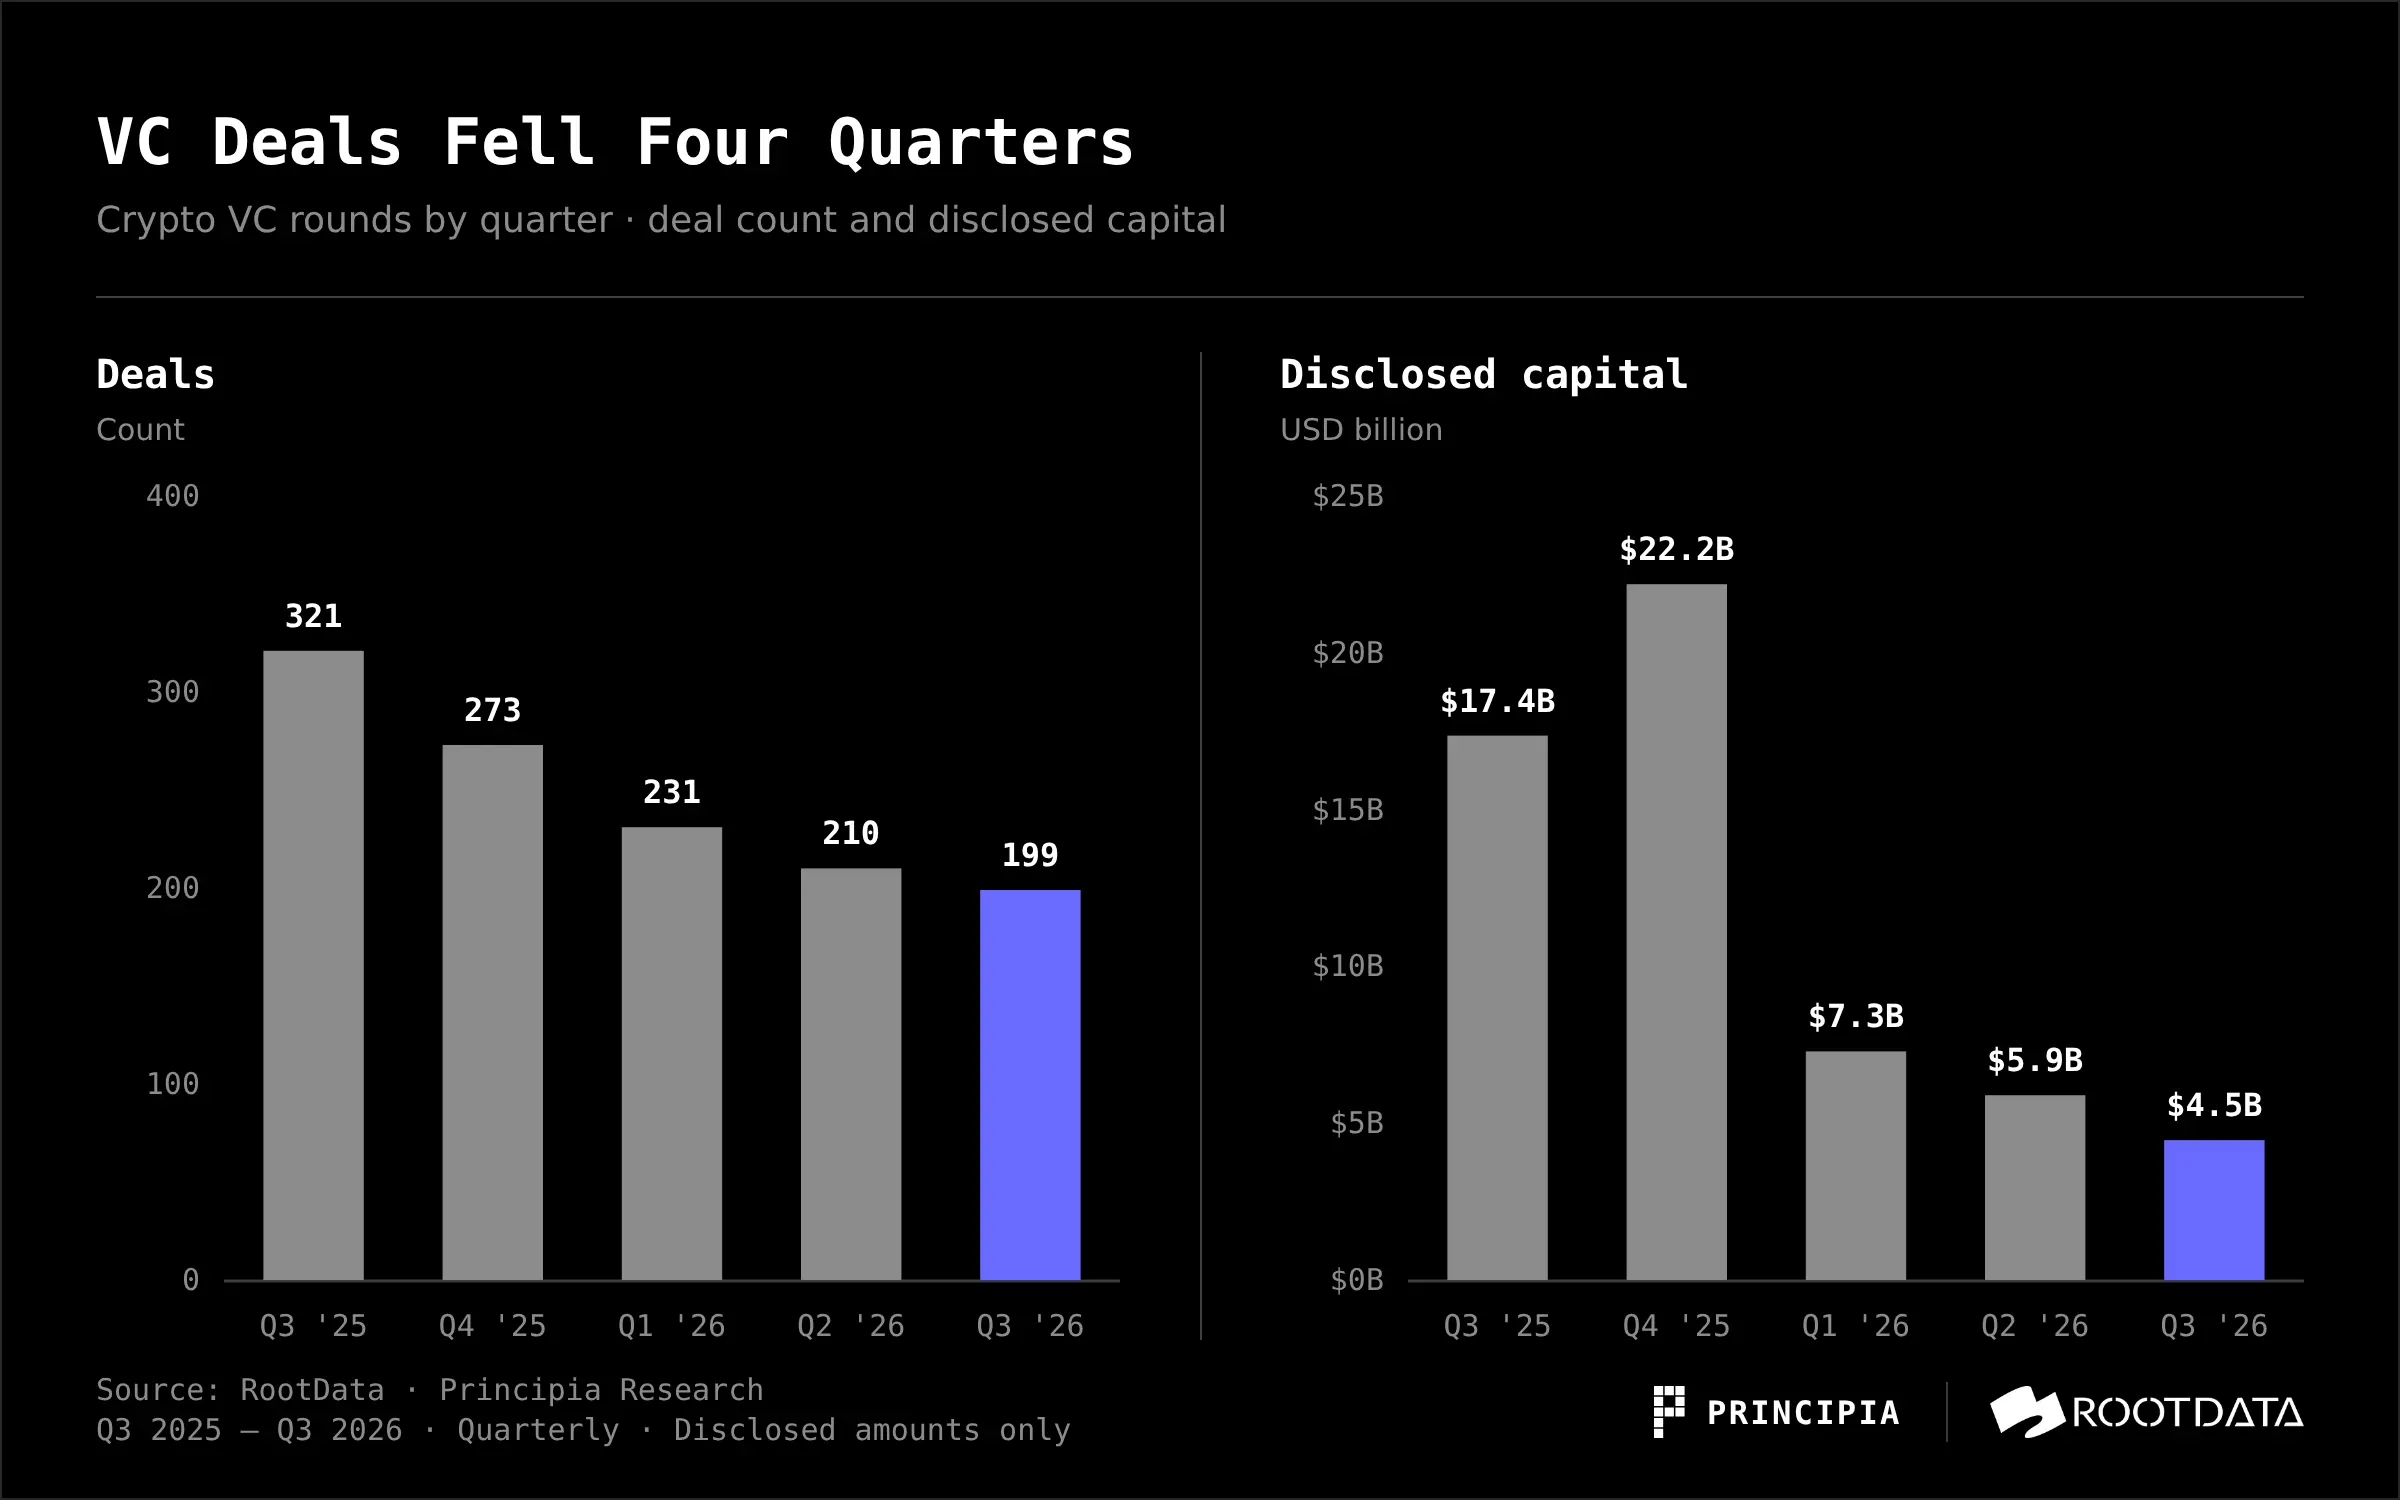
RootData recorded 199 financings. Of those, 116 disclosed an amount, for a disclosed total of $4.46 billion. Deal count was down 5% from the second quarter and had fallen for four straight quarters. Disclosed dollars were down 24% from the prior quarter and 74% from a year earlier. In the report’s reading, the market had not stopped. What changed was where the money went, and who supplied it.
The headline drop is not the same thing as a collapse in private equity checks. The year-ago base, the third quarter of 2025, was swollen by listed-company follow-ons and IPOs: Strategy about $2.52 billion, Forward Industries about $1.65 billion, Galaxy about $1.40 billion, and the Bullish IPO about $1.11 billion. After that wave of crypto-linked public financing receded, the year-over-year comparison fell 74%. Alongside that 2025 base, the report cites a fourth-quarter total of $22.19 billion that was similarly skewed, with nearly half from a single Dunamu acquisition of $10.3 billion. The November 10 article still treats the fourth quarter then open as something to watch, so that $22.19 billion is a comparison figure in the base-effect passage, not a reported result for the quarter still underway.
The equity cut runs the other way. The report removes listed follow-ons (post-IPO), IPOs and de-SPACs, mergers, token public sales, OTC trades, debt, and community rounds. It also removes unlabeled rounds above $100 million that it says were verified as secondary share transfers, token presales, listed-company financing, or debt. What remains is 144 equity financings and about $3.38 billion disclosed. That is above the second quarter’s roughly $3.02 billion across 168 deals, and above the third quarter of 2025’s roughly $2.50 billion across 226 deals. Equity dollars were up 12% quarter on quarter and 35% year over year. Equity deal count was down 14% and 36% on those same comparisons. Fewer transactions. Larger ones.
Inside the quarter, the path was a handful of large checks. July was the hot month: $2.37 billion across 72 deals, including $400 million each for Crypto.com, Ionic Digital, and Securitize. August was the cold month: $0.72 billion across 63 deals. September recovered to $1.37 billion across 64 deals, mainly from $300 million for Polymarket and $200 million for Félix. Later, the report describes 1789 Capital leading a Polymarket round of about $1 billion, contributing about $300 million, at a $21 billion valuation. It does not say whether that contribution and September’s Polymarket figure are the same check. The month-to-month swing is presented as the product of large deals, not as a broad reopening.
The report treats the split between a rising Bitcoin price and a cooler primary market as the fact worth watching. Its stated reason is competition from AI. Compute and models need large sums, and the authors say the market’s growth expectations are higher there. With LP allocations limited, some capital that might have gone to crypto venture is, in their view, turning toward AI. They cite three institutional moves as fitting that shift. Those moves are not presented as proof that AI caused the deal count to fall. On July 8, 2026, Paradigm said it had closed a fourth fund of $1.2 billion, extending the mandate from crypto to AI, robotics, and other frontier fields while continuing to invest in crypto. IOSG founding partner Jocy Lin separately set up AI-focused IOSF Ventures; the report does not date that launch. On October 22, 2026, a16z Crypto was renamed a16z Frontier, and the new fund’s scope was extended to AI, autonomous machines, and other frontier technology, again while crypto investing continued.
Only after those drivers does the older script come in. The similarity is the expectation that a higher coin price and a busy venture market travel together. The difference is this quarter’s tape. Bitcoin was up about 43% on the window above, while disclosed primary dollars were down 24% from the prior quarter and 74% from the inflated 2025 base. On the cleaned equity cut, dollars rose and the deal count fell, and the remaining checks sat later. A price move and a financing move in the same months do not establish which one caused the other. The report says the old line — coin price up, venture market hot — failed for the moment. It does not call a top or a bottom.
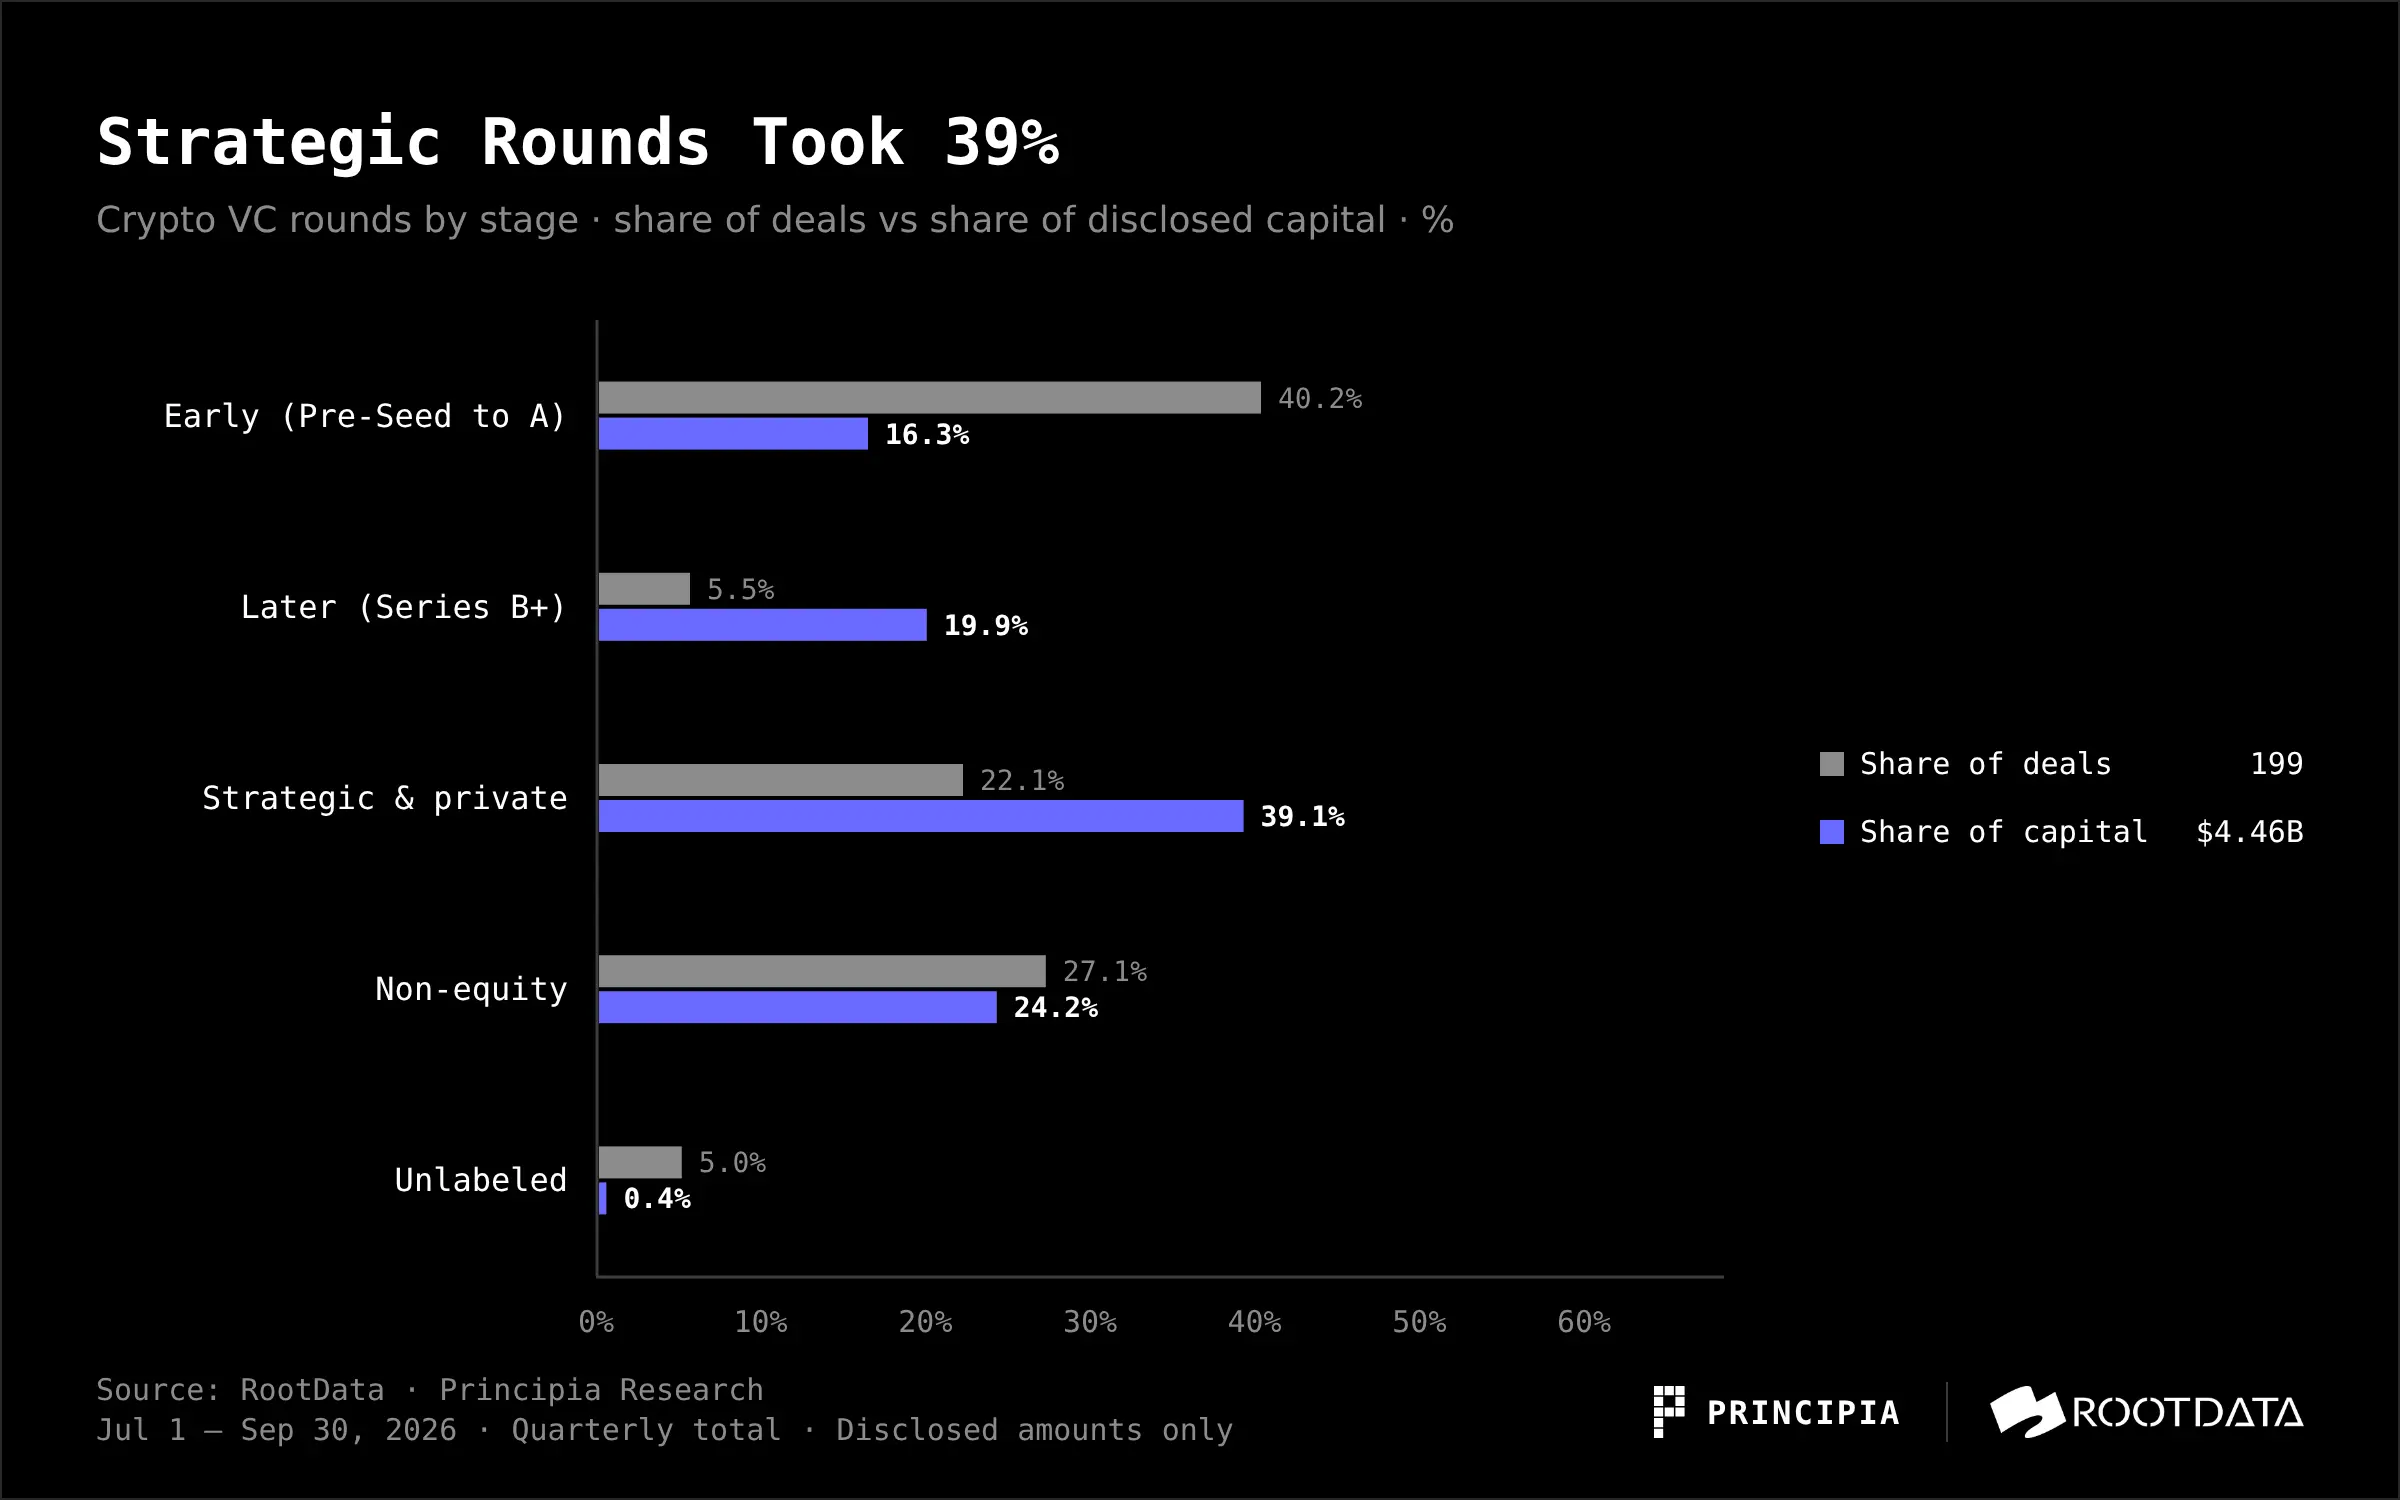
Capital sat late. Strategic rounds and private rounds took about $1.75 billion, close to 40% of disclosed dollars. Early rounds were the busiest by count: 80 deals, about 40% of all transactions, and only about $0.73 billion, roughly one-sixth of disclosed dollars. Deals outside the early stage took about 84% of disclosed money.
Checks from $20 million up to but not including $100 million totaled 25 deals and about $1.15 billion, versus 19 deals and about $0.77 billion in the second quarter. Seven of this quarter’s middle checks were OTC, debt, listed follow-ons, or acquisitions. Equity-only, the middle was 18 deals and about $0.87 billion — the same count as the second quarter’s 18 deals and about $0.73 billion, with dollars up about 19%, and still below the third quarter of 2025, when that band was 31 deals and about $1.03 billion.
The median disclosed amount rose from $6.0 million to $8.0 million. Deals of $100 million or more fell from 17 to 13. The top ten deals’ share of disclosed dollars fell from 62% to 57%. The clearest drop in count was among disclosed deals under $5 million. The report does not give that small-deal count.
The report links the later-stage tilt both to lower risk appetite and to a change in who is still writing checks. Some crypto-native managers had stopped new investments, were winding down, or had turned toward AI.
In December 2025, after the SEC sued Shima Capital, the founder reportedly told portfolio companies in an internal email that he was leaving and that the fund would be wound down in an orderly way. In June 2026, AGV, the gaming investment program under Arbitrum DAO, proposed making no new investments and only managing the existing portfolio. The proposal passed in early July. About 143.7 million ARB is to be returned to the DAO treasury in batches. In October 2026, Deus X Capital stopped operating and is set to liquidate formally on January 31, 2027. CEO Tim Grant became CEO of the AI company TensorX. Around the end of that same month, Verda Ventures, focused on stablecoin infrastructure, stopped backing new projects after its founder joined Tether and shifted to serving only the existing portfolio.
Traditional finance and strategic capital filled some of that space. The report says the money went to licenses, clearing, and trading access rather than to a new narrative. Citadel Securities invested $400 million in Crypto.com at a $20 billion valuation. Nasdaq Ventures agreed to invest $100 million in Payward, Kraken’s parent; Bloomberg, as cited by the report, put the corresponding valuation near $21 billion. Tiger Global led a $180 million Series B for Augustus. SBI Holdings led a $76 million Series C for EDX Markets and a $125 million Series C for Gauntlet. The Polymarket round led by 1789 Capital is the one noted above.
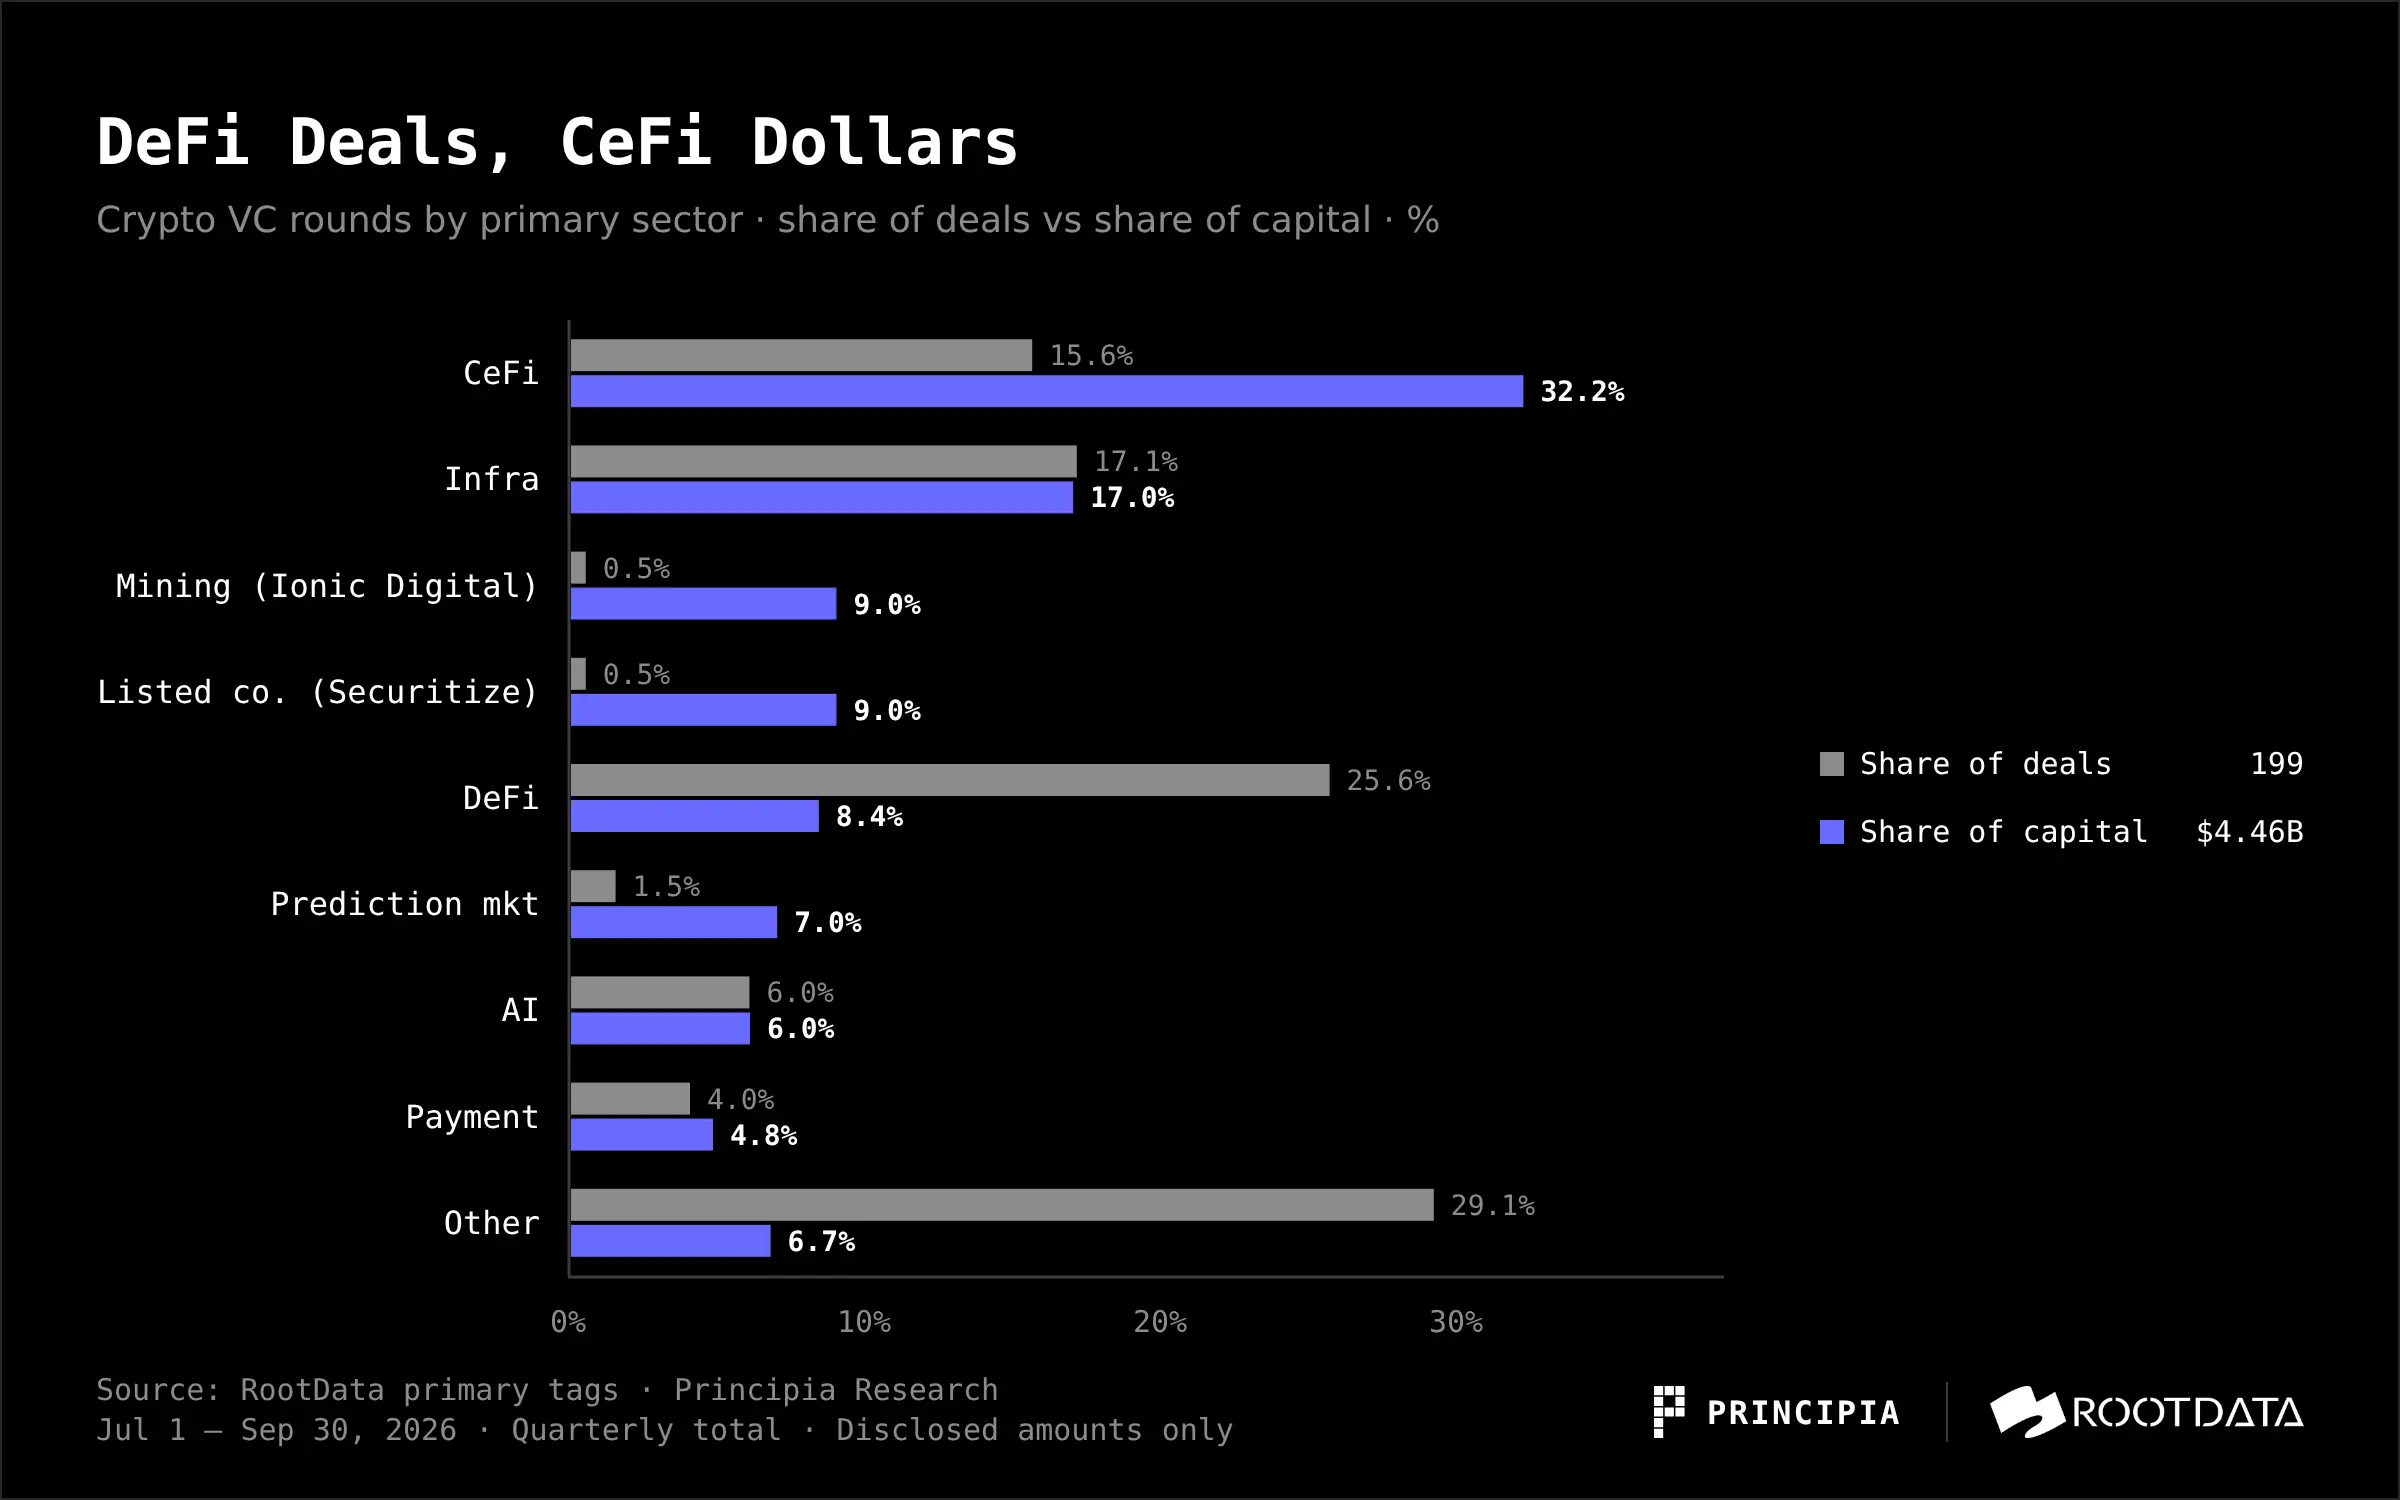
By RootData’s primary tag, CeFi was first in dollars: 31 deals, $1.44 billion, 32% of the disclosed amount. The large CeFi names the report groups as trading, brokerage, and clearing access are Crypto.com, Kraken, Augustus, Alpaca, and EDX Markets. DeFi had the most deals, 51, and only $0.37 billion, or 8%. Disclosure is part of that gap: 25 of the 51 DeFi deals published an amount. Even with that caveat, the report describes DeFi as mostly small, early, and protocol-oriented. Infrastructure was second: 34 deals and $0.76 billion, with Ripple — a $275 million senior unsecured note for Ripple Prime — plus Prime Intellect and Gauntlet named as examples. Two further single checks of $400 million each carried a tag on their own: bitcoin miner Ionic Digital, and Securitize, which listed on the New York Stock Exchange through a SPAC. Consumer activity was nearly empty. The gaming primary tag had 3 deals and about $5.9 million.
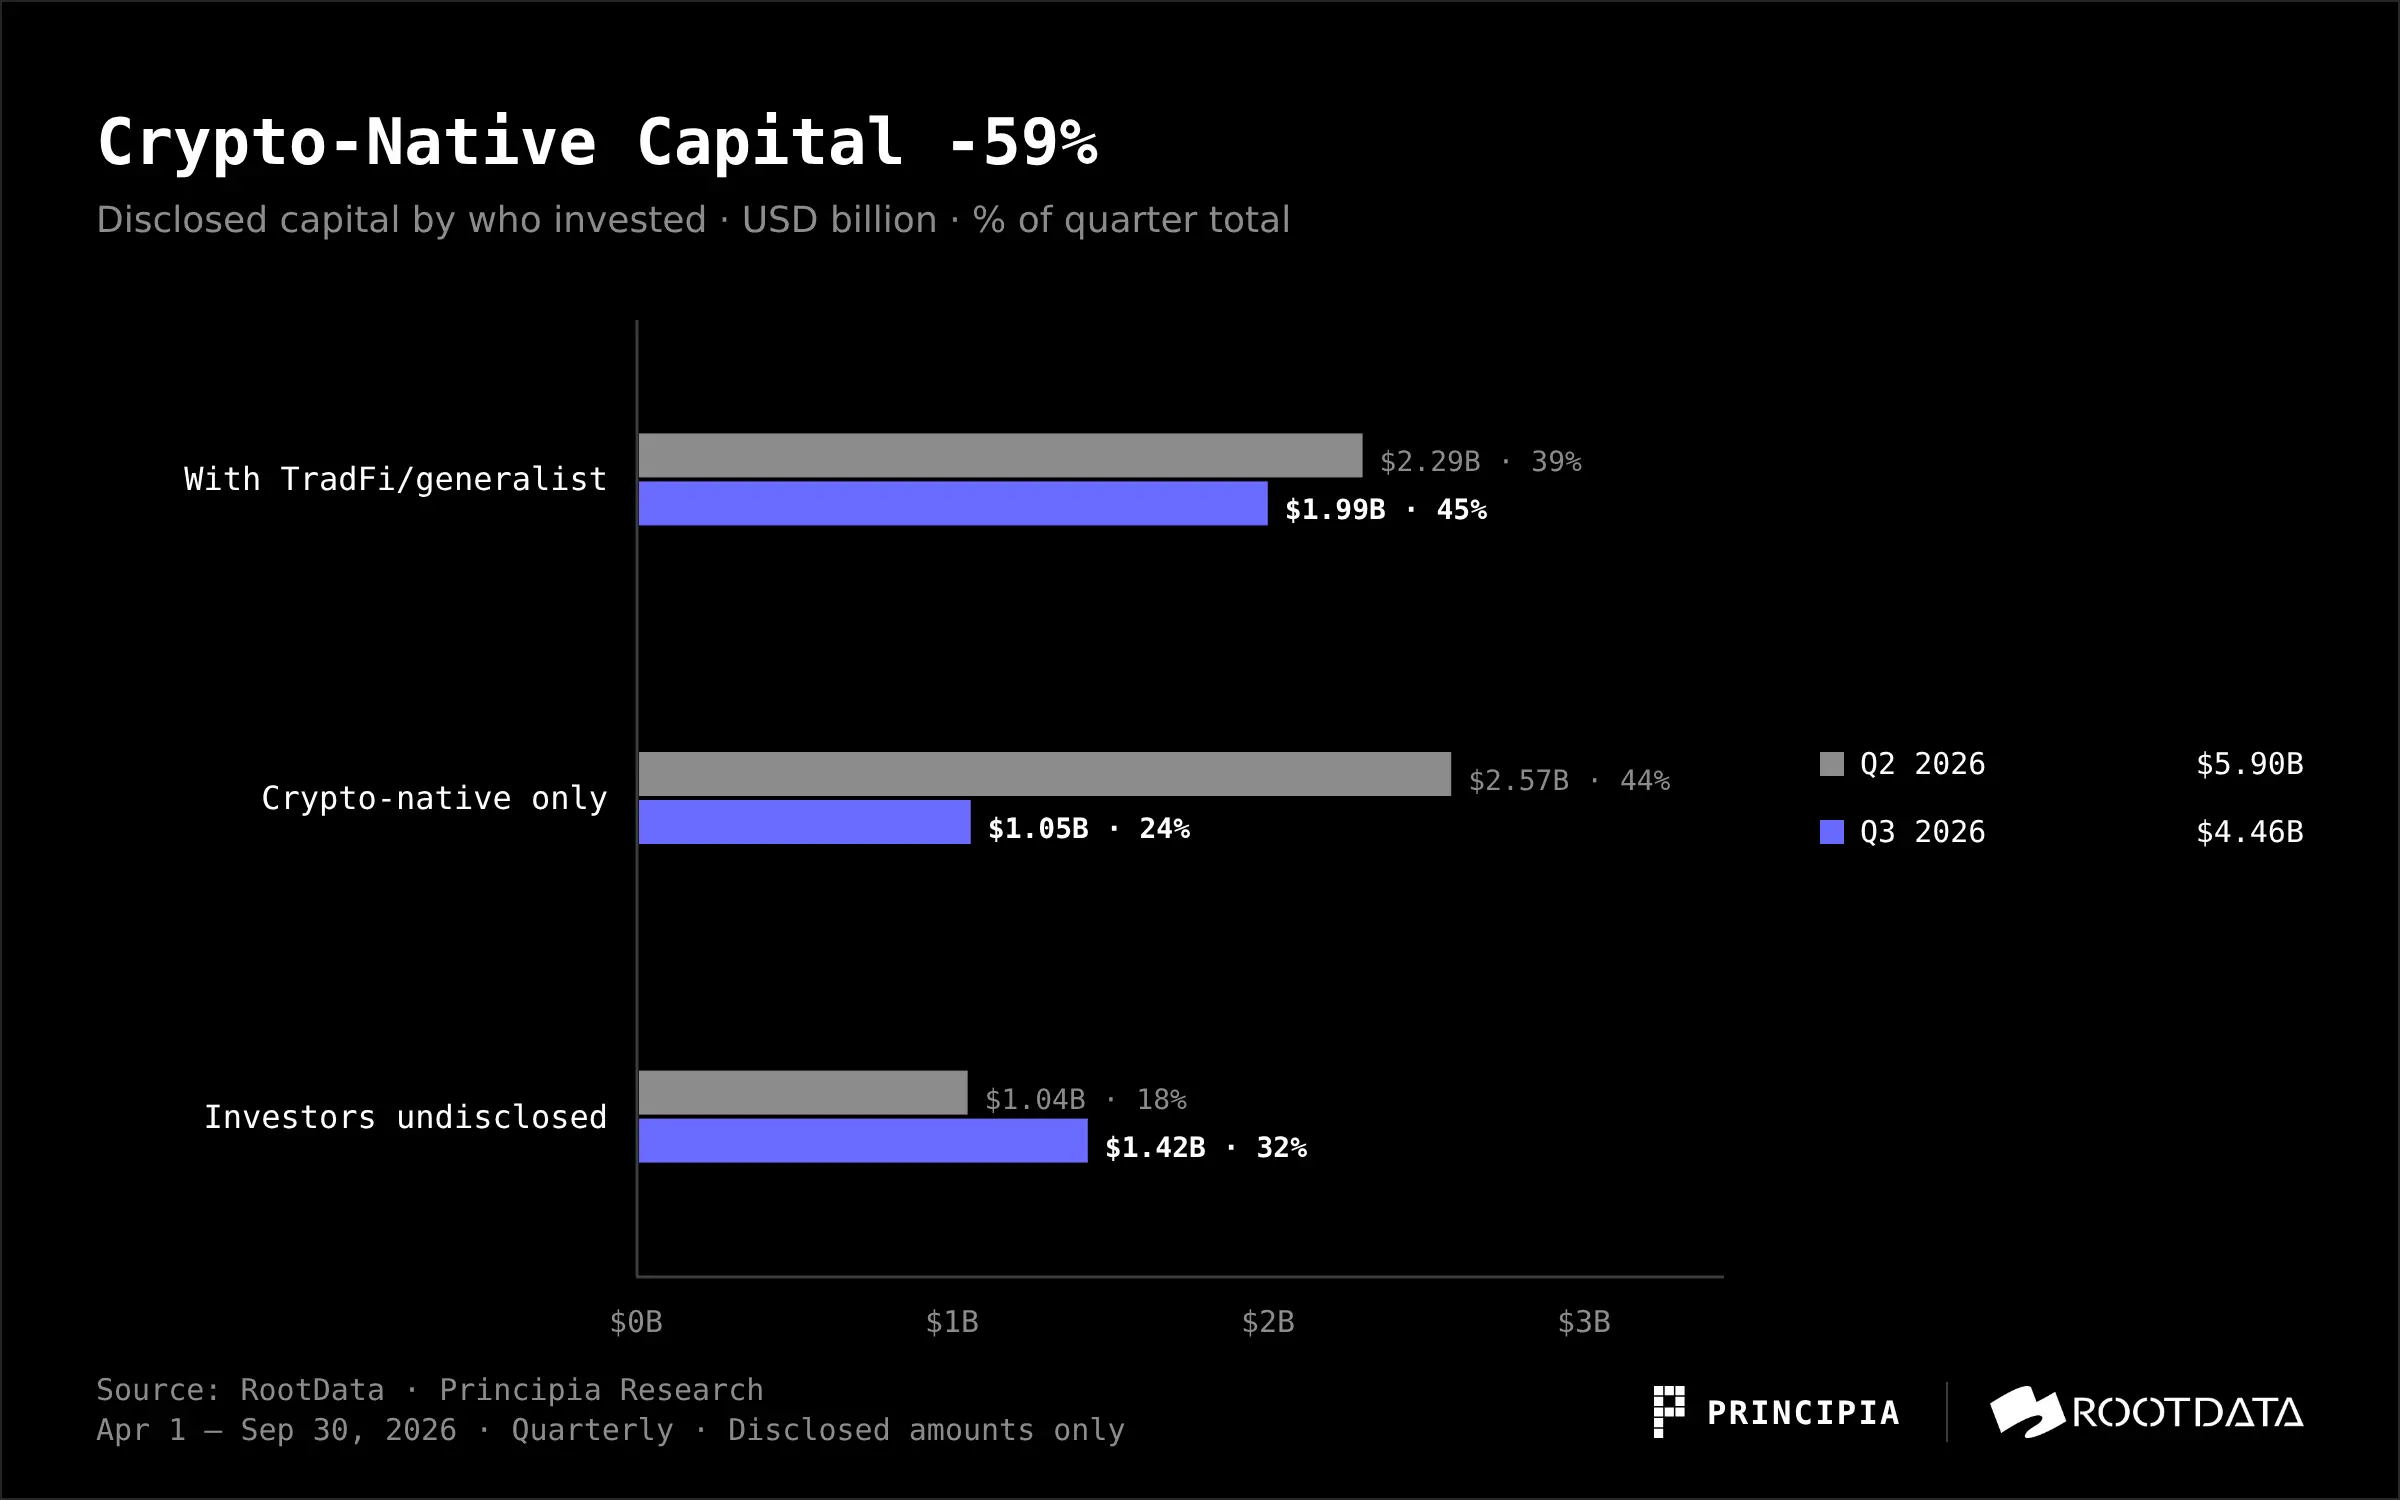
Deals backed only by crypto-native capital saw disclosed dollars fall from $2.57 billion in the prior quarter to $1.05 billion, a drop of nearly 60%. Their share fell from 44% to 24%. Deals with traditional-finance or generalist capital rose from 39% to 45% of disclosed dollars. The report defines that second group as banks, exchanges and market infrastructure, broker-dealers, asset managers, technology giants, trading firms, and generalist or fintech venture firms. The names it places behind the quarter’s largest deals are Citadel Securities, Nasdaq, 1789 Capital, Tiger Global, Peak XV, SBI, Intel Capital, and ICONIQ. It does not assign a separate dollar figure to each of those names beyond the rounds already listed.
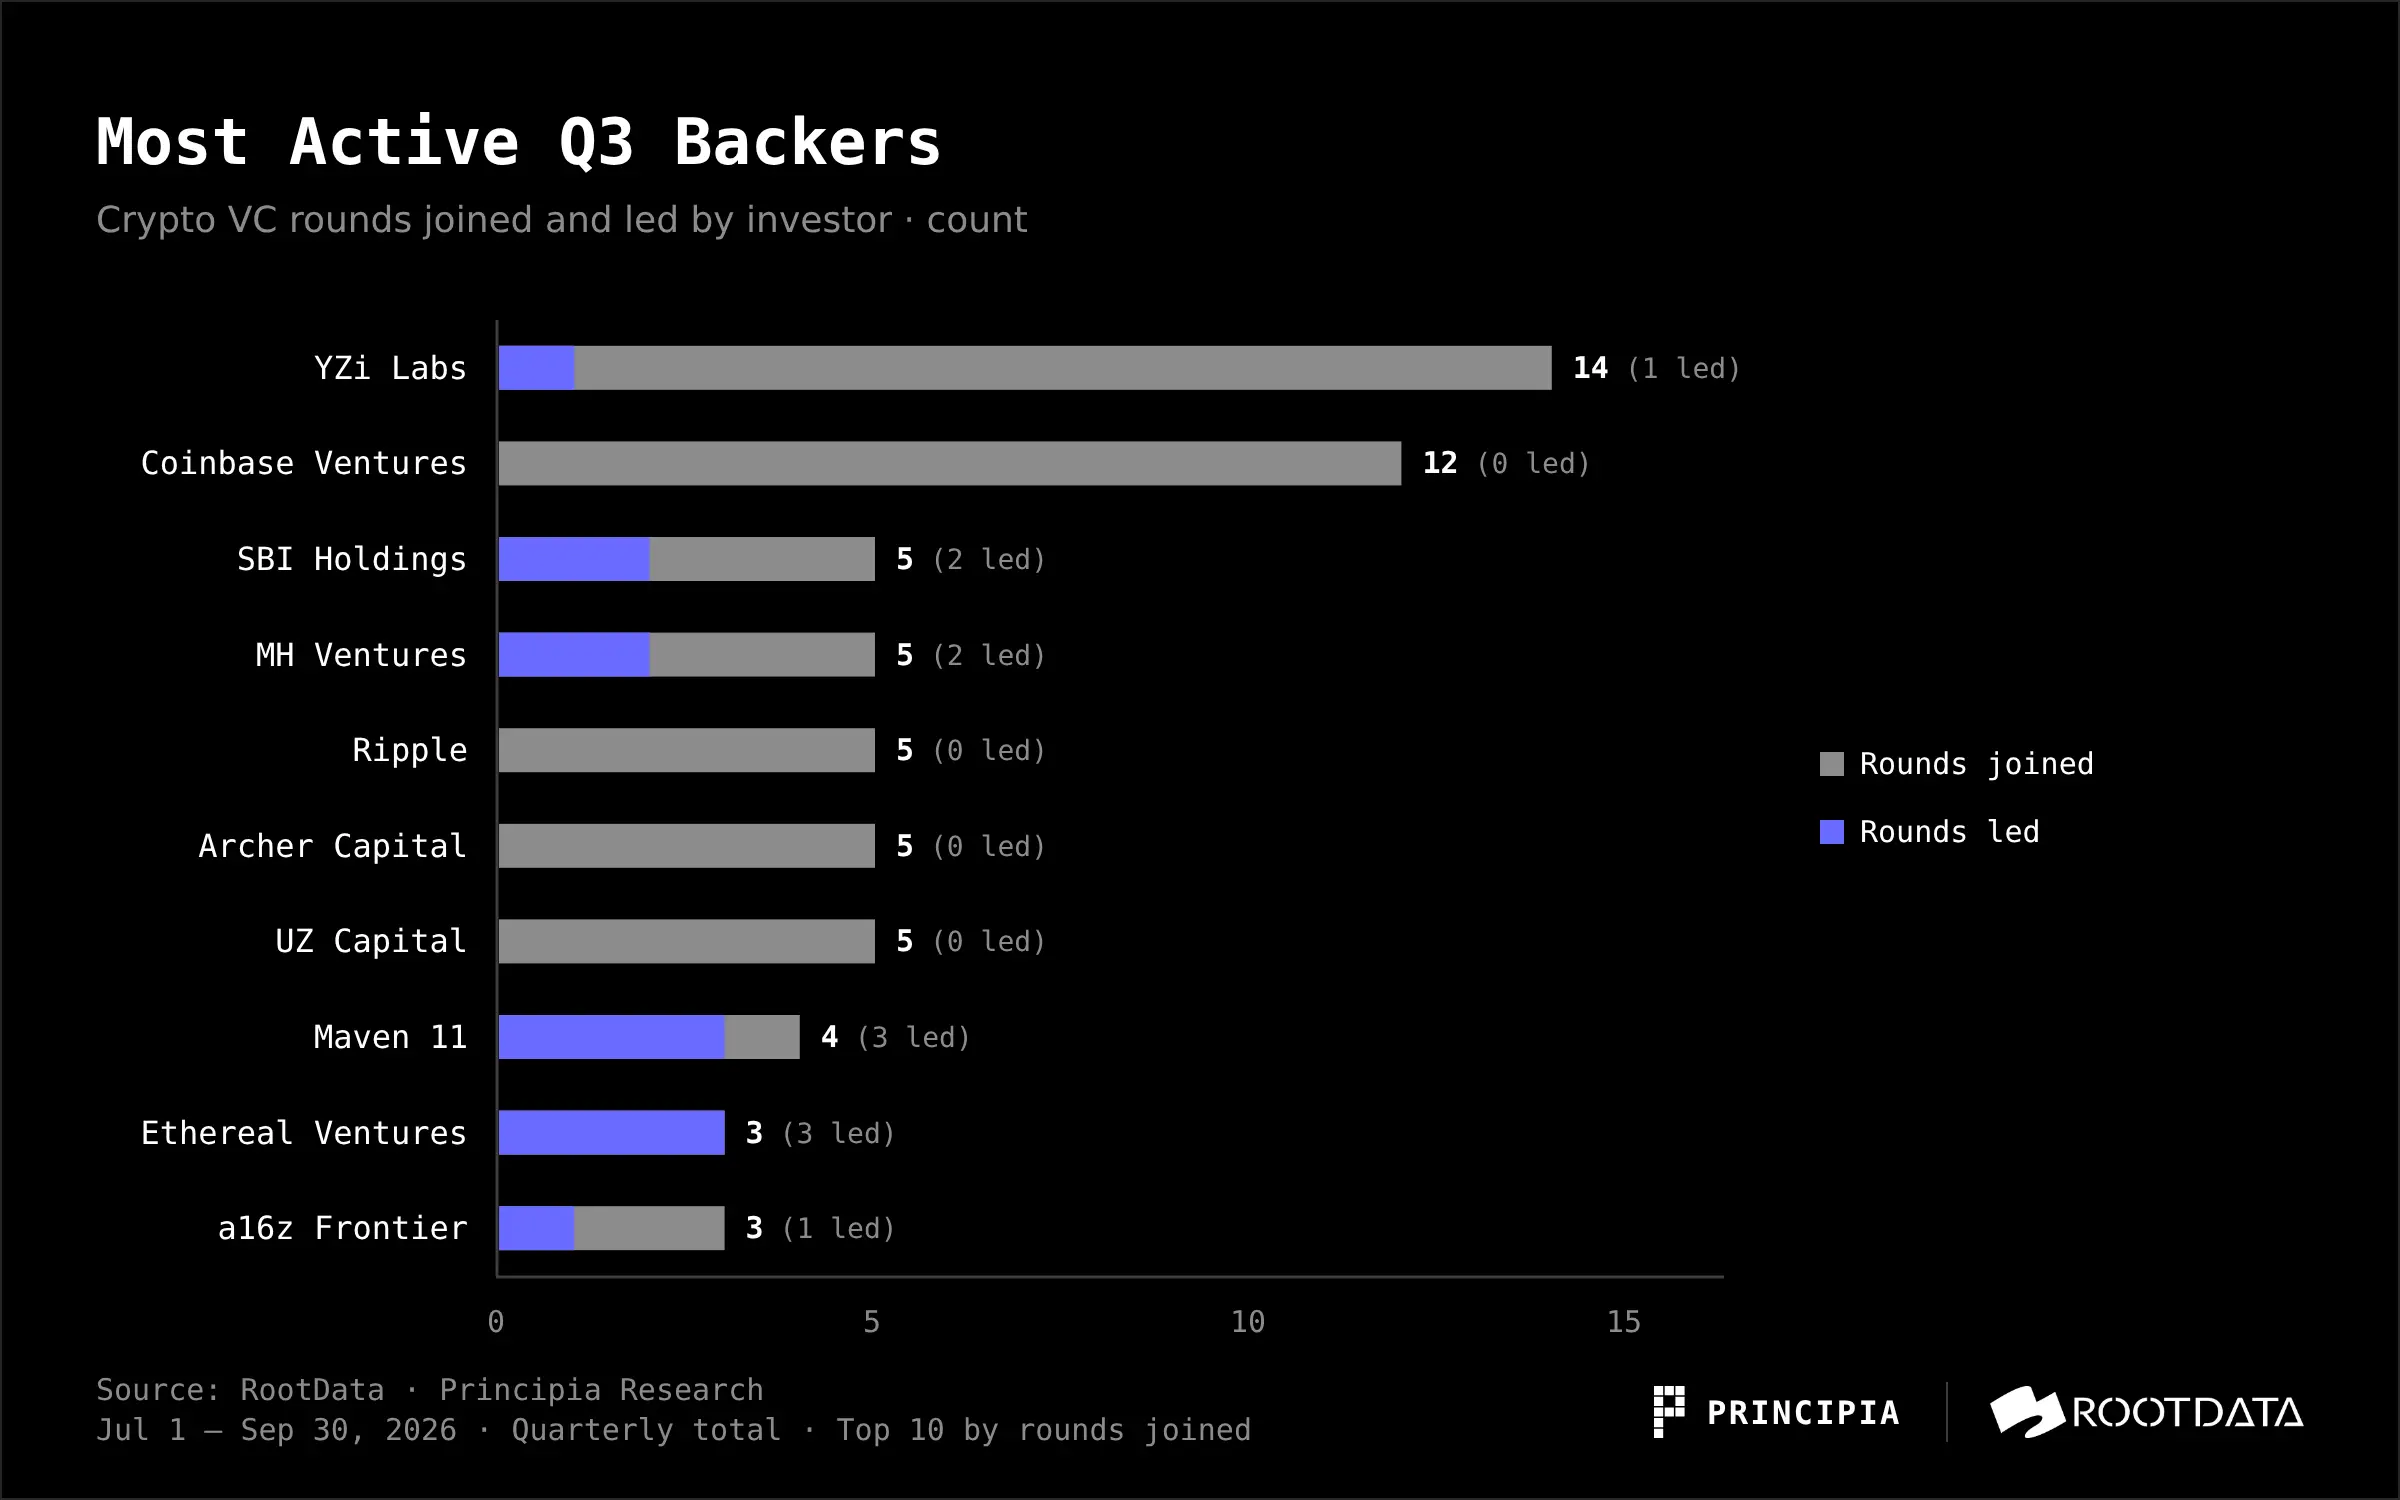
Counted by appearances, the picture is different. YZi Labs and Coinbase Ventures were the most active, but the report says both mostly incubate and follow, and almost never lead. It does not publish their third-quarter appearance totals. Relative to the second quarter, the lead group changed. That quarter’s most active names were Coinbase Ventures (13 times), Animoca Brands (12), and a16z Frontier, formerly a16z Crypto (8). Paradigm also led 4 deals then. This quarter, the report says more of the pricing power sat with the traditional institutions named above.
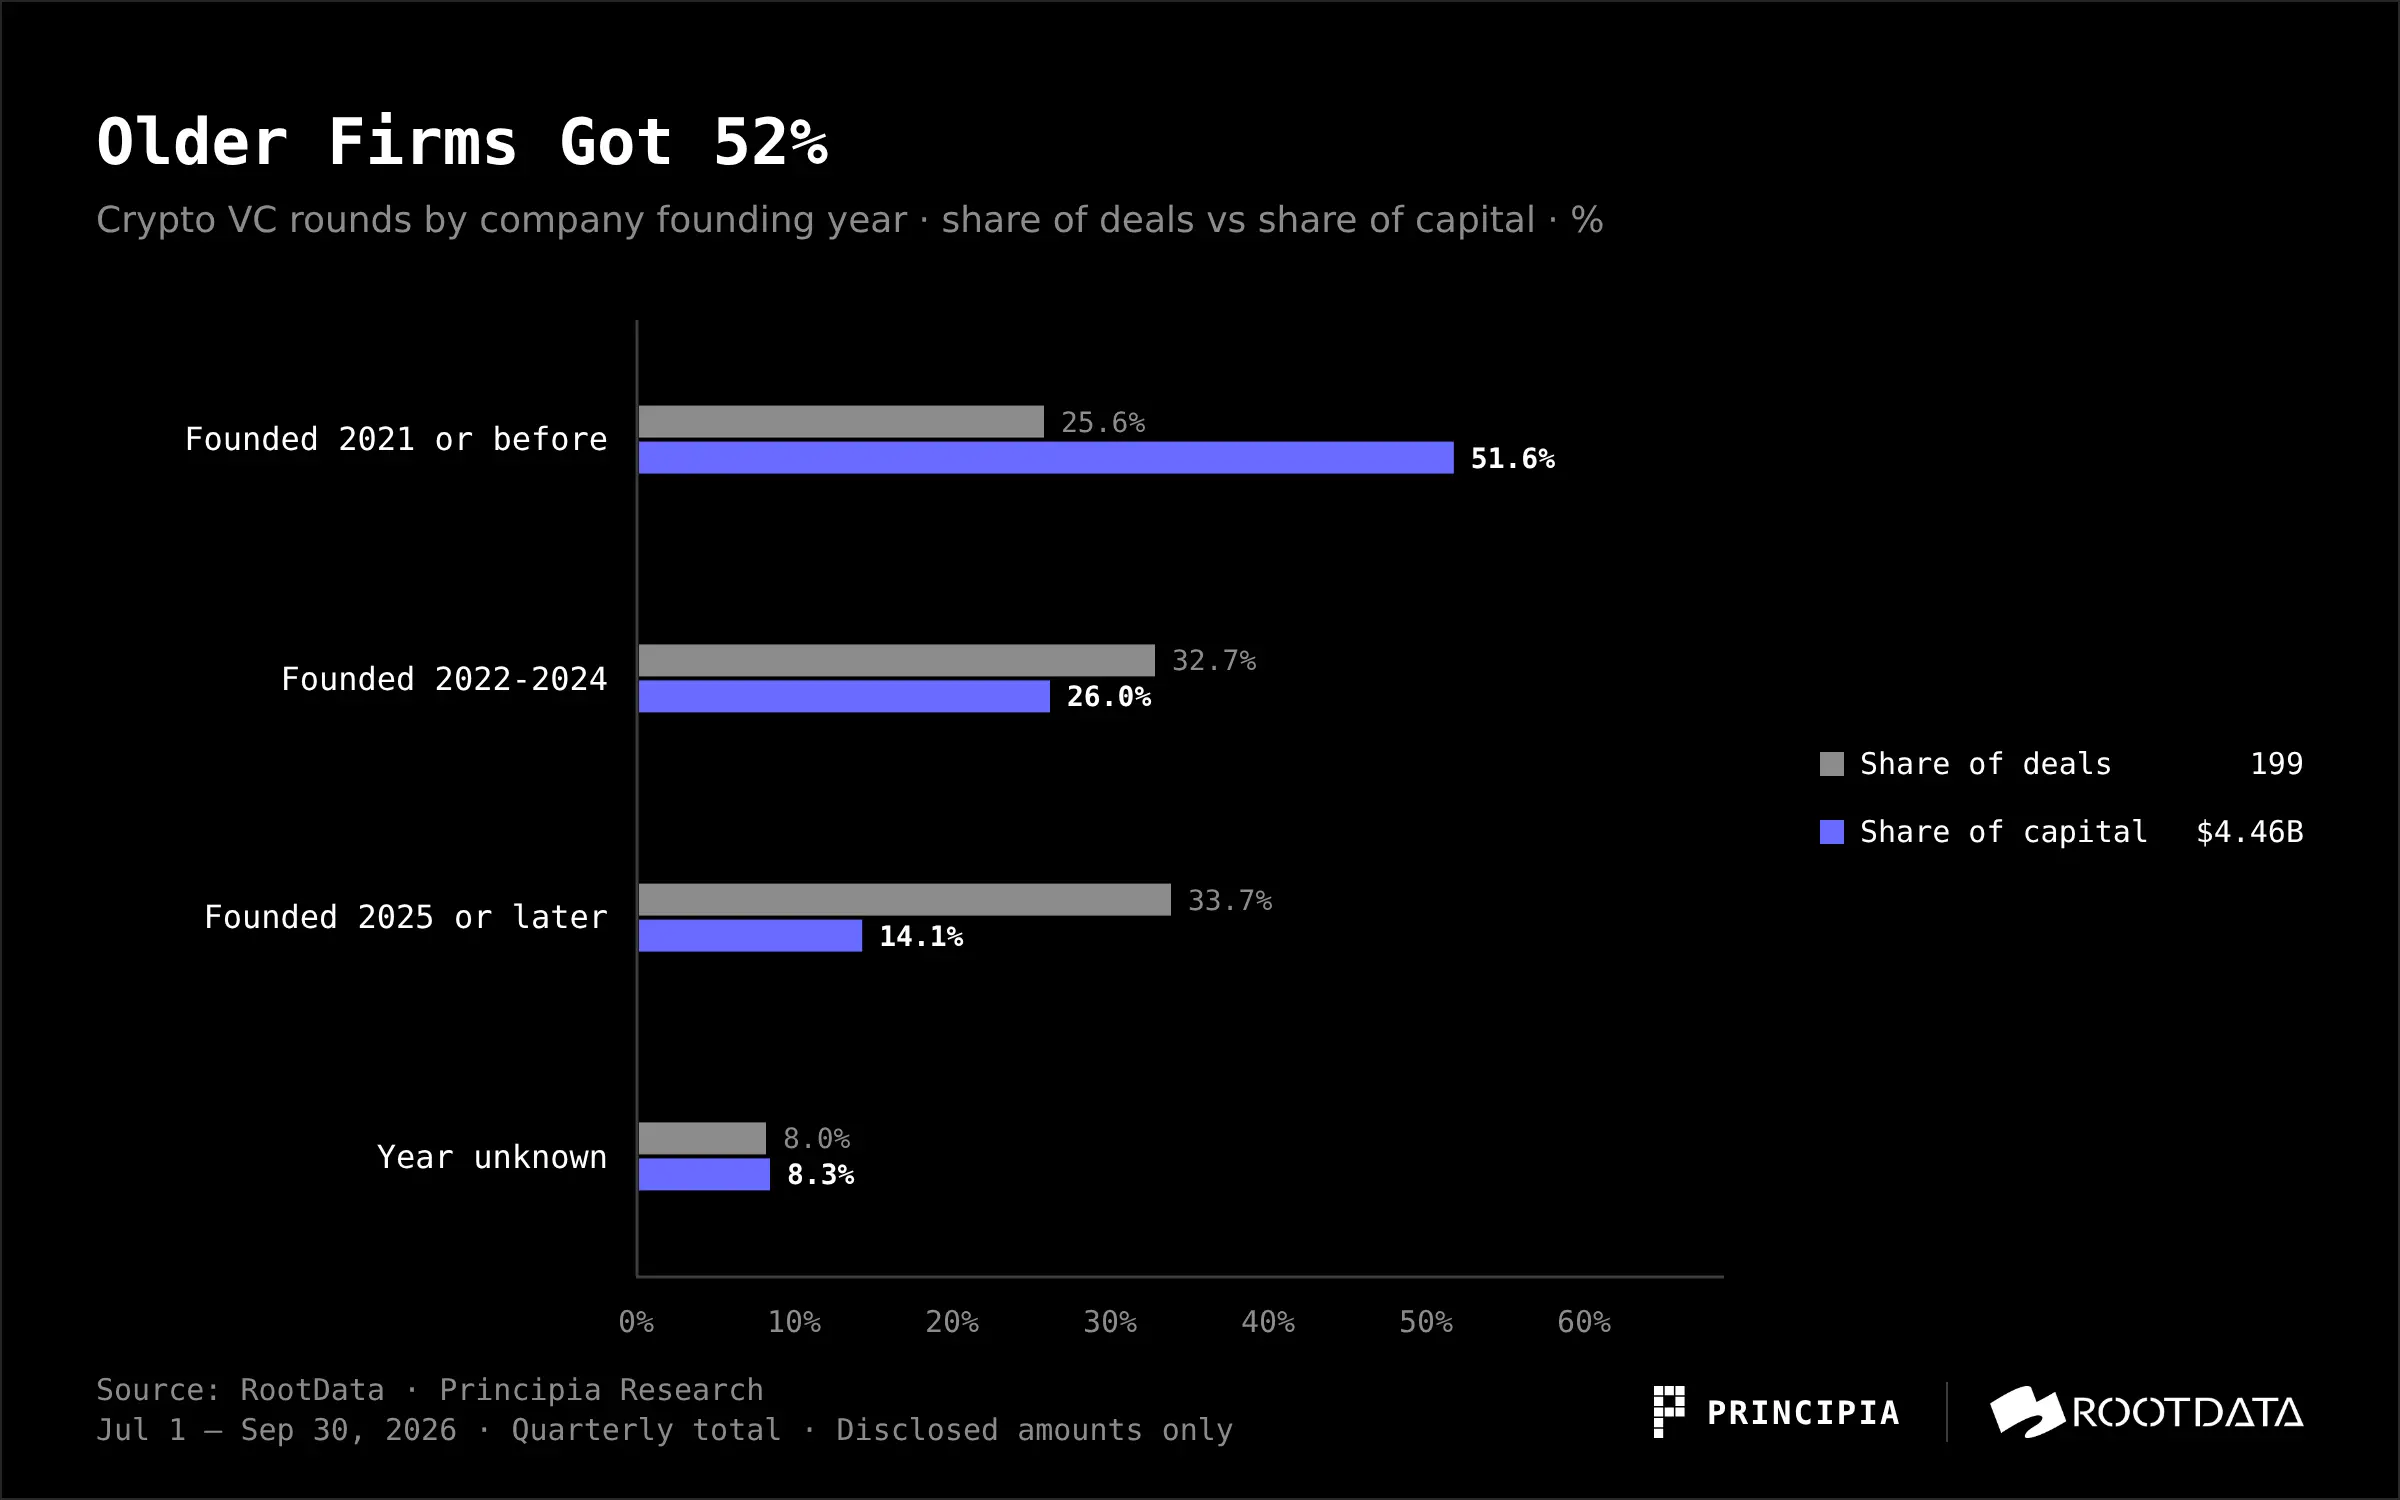
Company age split along the same line as stage. Firms founded in 2021 or earlier closed 51 financings and took $2.30 billion, more than half of disclosed dollars. Firms founded after 2025 had the most deals, 67, and only $0.63 billion. The familiar large-check names are Crypto.com (founded 2016), Kraken (2011), Ripple (2013), and Securitize (2017). The report’s point is that they already have revenue, licenses, and businesses that can be valued, which matched the quarter’s preference.
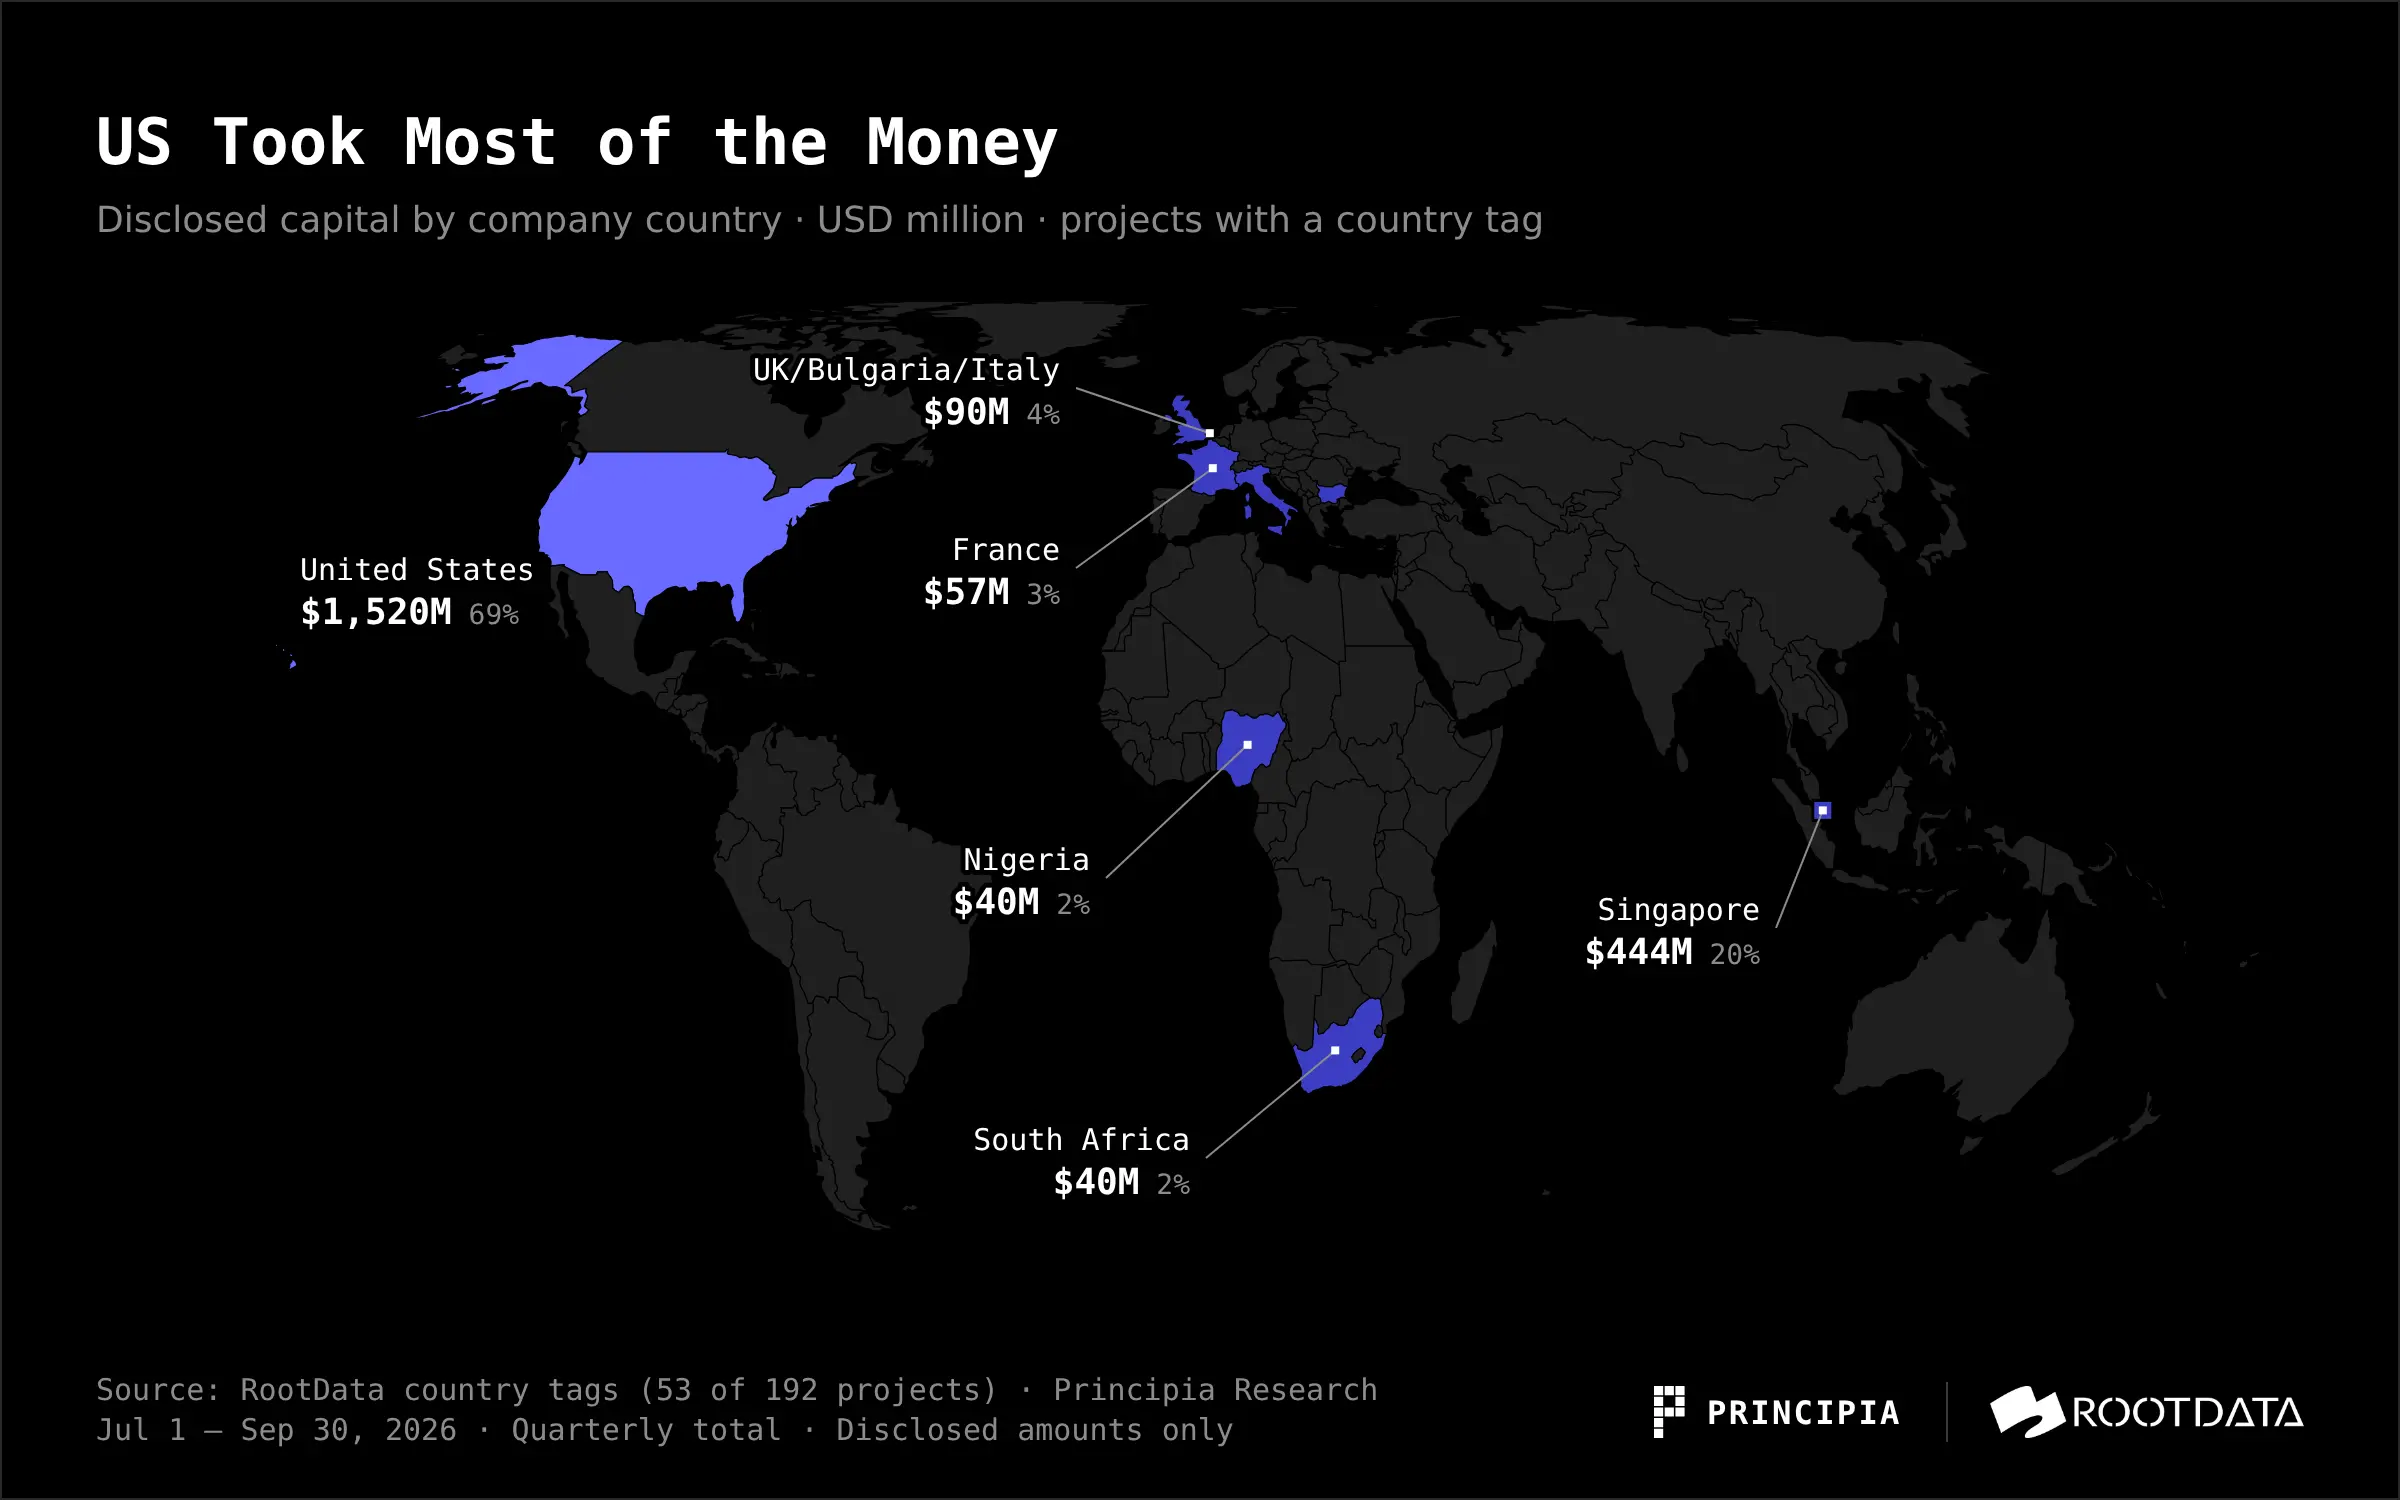
Geography is a partial sample, and the report says so. RootData’s country field covers 53 of 192 projects, or 28%, corresponding to 55 deals and $2.19 billion — about half of the quarter’s disclosed dollars. Inside that slice, the United States was 28 deals and $1.52 billion. Singapore was 10 deals and $444 million, of which Crypto.com’s single check was $400 million. The rest is scattered: the United Kingdom, Bulgaria, and Italy at $90 million each; France at $57 million; Nigeria and South Africa at $40 million each. Hong Kong had 3 deals and Japan 2, both for amounts the report only calls very small. Coverage this thin cannot map the whole market. On the deals that do carry a country, money in the sample is still heavily concentrated in the United States, and the large Asian check is mainly a Singapore exchange.
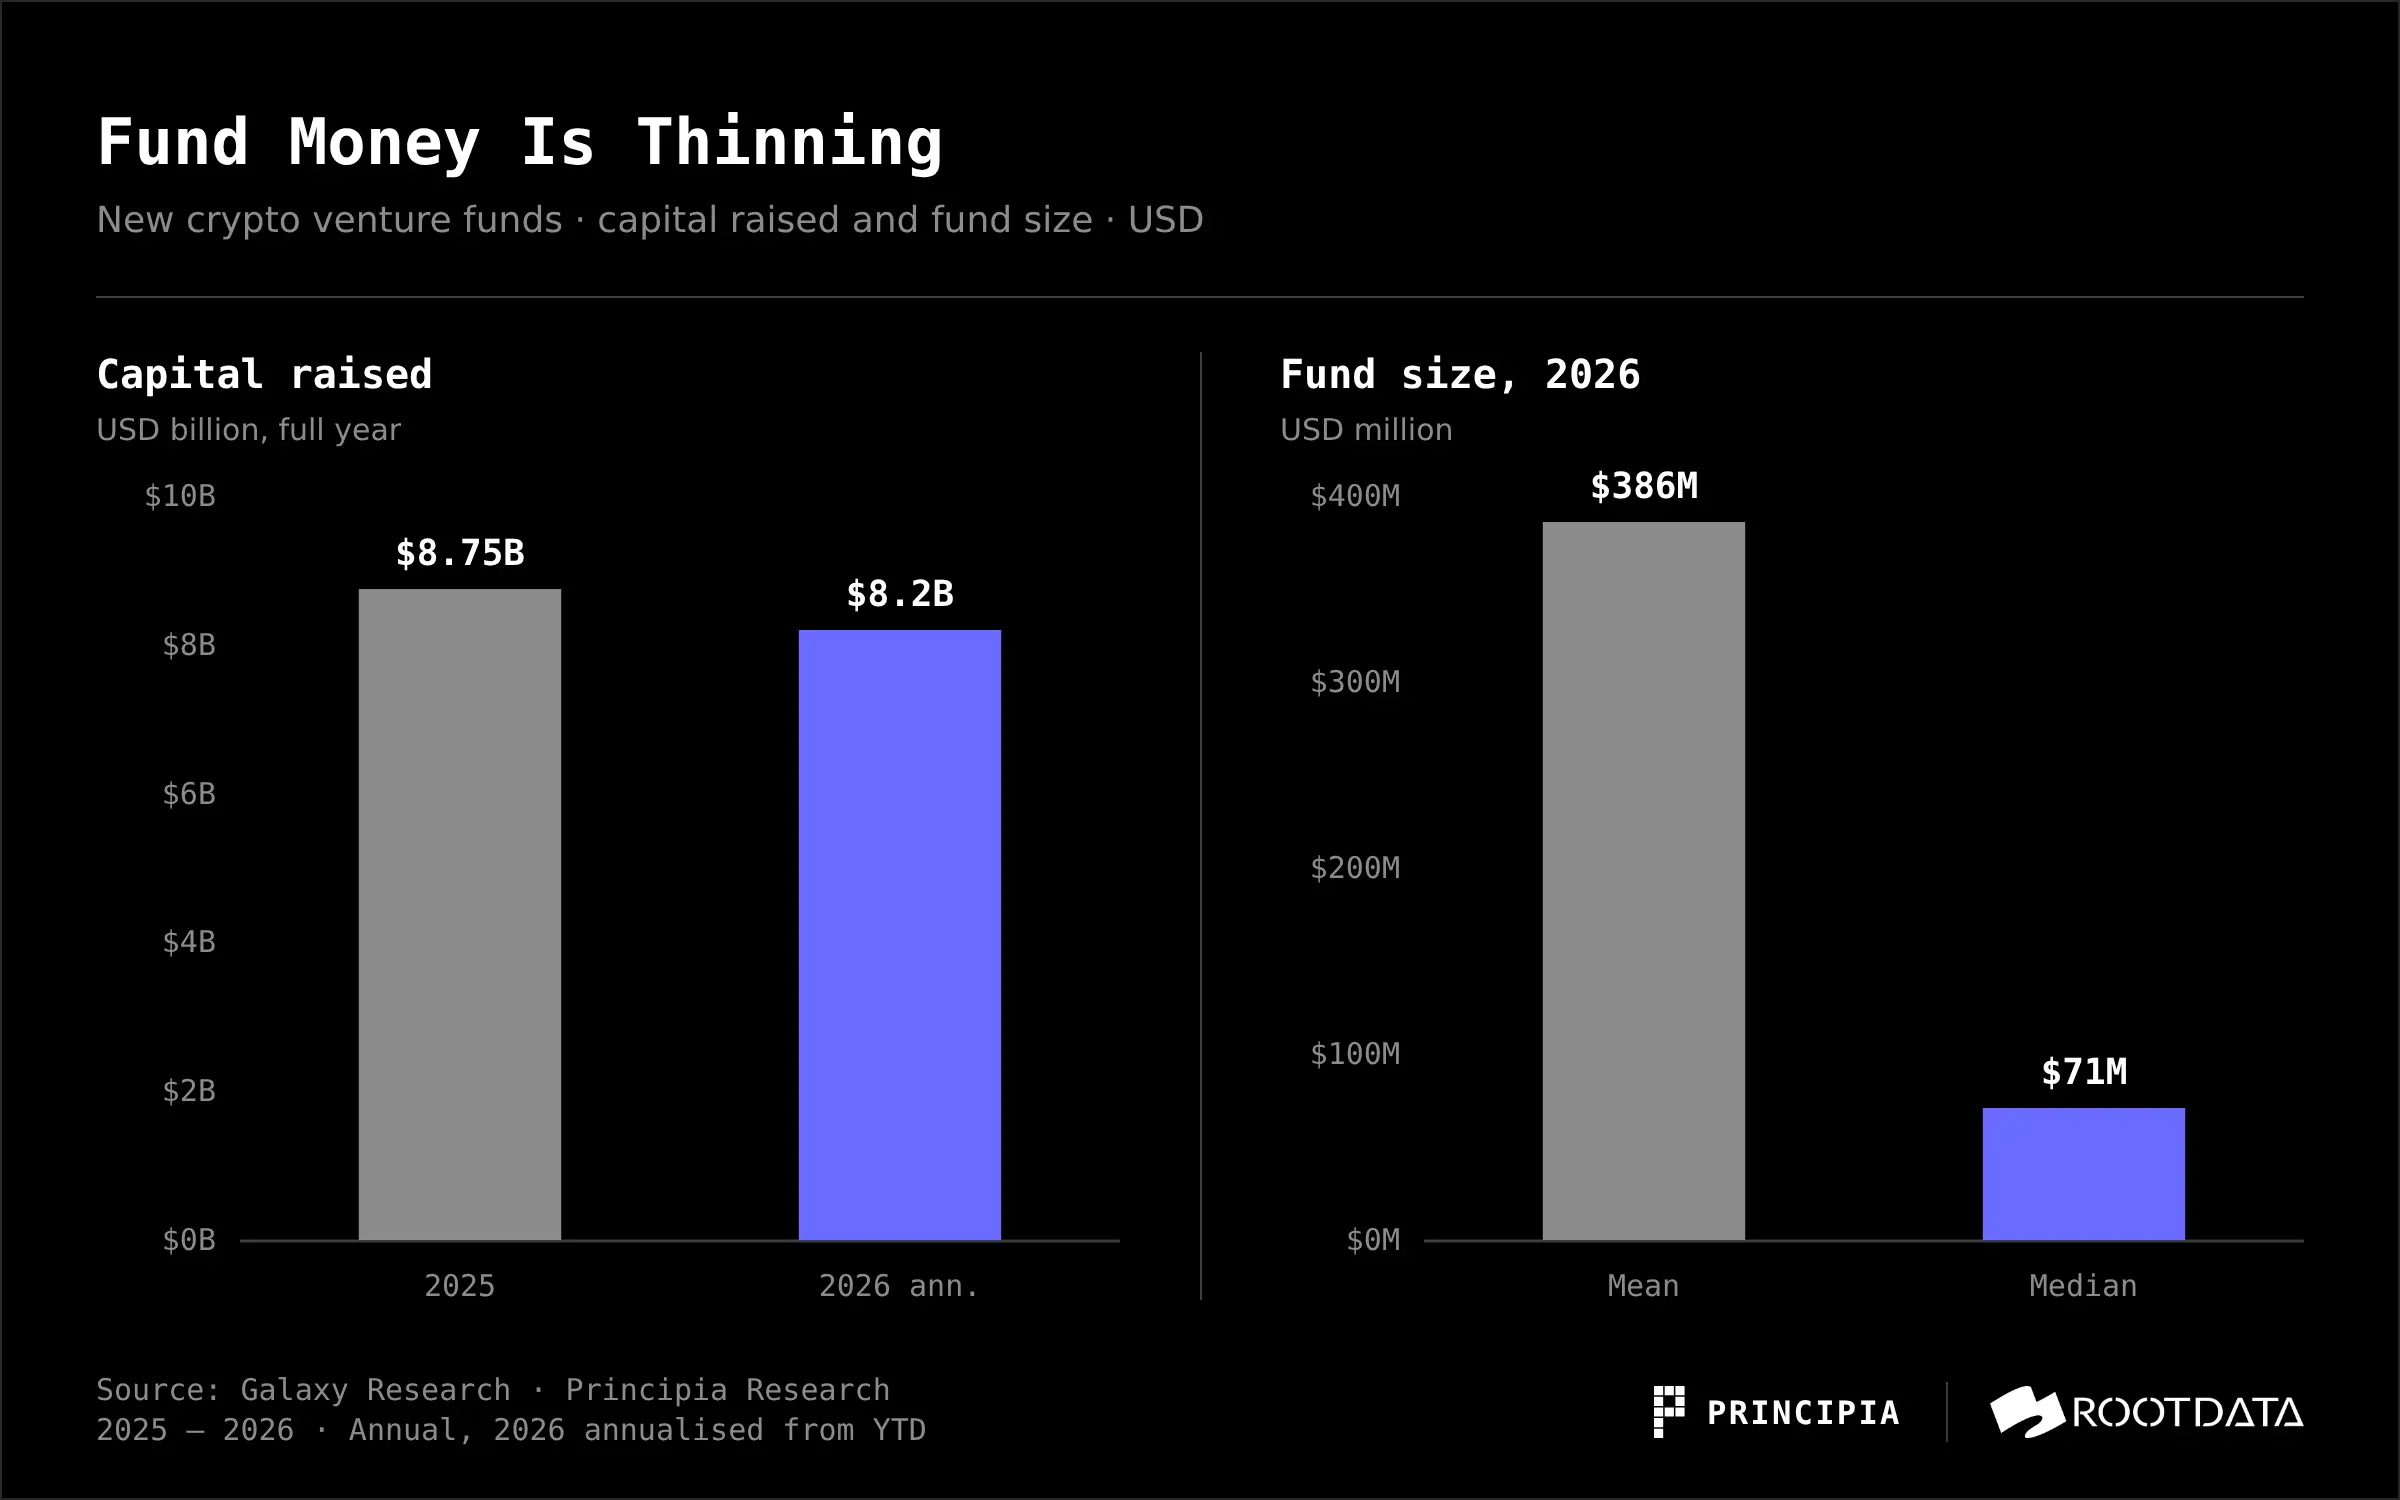
How much the primary market can deploy still depends on what funds raise. Citing Galaxy Research, the report counts only 3 new crypto venture funds closed in the quarter, about $1.3 billion combined — the fewest new funds since the third quarter of 2019. On an annualized basis, fundraising this year is about $8.2 billion, slightly under 2025’s $8.75 billion. Year to date, the average new-fund size is about $386 million and the median is $71 million. Most new funds are not large. A few big ones pull the average up.
The report treats difficult fundraising and a cooler investment pace as two sides of one allocation problem. Spot ETFs, digital-asset treasury companies, and AI are all competing for LP money. Its judgment — labeled as a judgment — is that tight LP capital will make GPs more cautious: favor follow-on rounds for companies already backed, and prefer businesses with revenue and licenses. That is the shape it says this quarter already showed. It is not a claim that the next quarter must repeat it.
The article’s own summary: venture activity cooled; money preferred financial pipes that can charge fees, hold licenses, and clear; more of the pricing sat with traditional financial institutions; and cold fundraising from LPs leaves later startup rounds looking difficult. For founders, its reading is that a large round comes later and looks closer to a mature-company raise — revenue, licenses, and distribution rather than narrative — with smaller first checks. For investors and LPs, its reading is that a firmer Bitcoin price did not automatically pass through to the primary market. The rebound in mid-range dollars, from $20 million to under $100 million, came with a flat equity deal count, and the report says more quarters are needed before that can be treated as a trend.
It leaves three questions for the fourth quarter, open as of the November 10, 2026 publication. Whether traditional finance keeps participating: it was involved in 45% of disclosed dollars this quarter, and the report does not decide if that is a structural change or a cluster of large deals. Whether the coin price reaches early rounds: only a rebound in the number of small early deals would, in its view, show the startup end actually warming. And policy and fundraising: progress on the CLARITY Act, which the article does not further describe, and whether new funds can close before year-end.
Original article: Q3 加密融资继续降温,资金转向后期与战略轮, ChainCatcher, November 10, 2026.