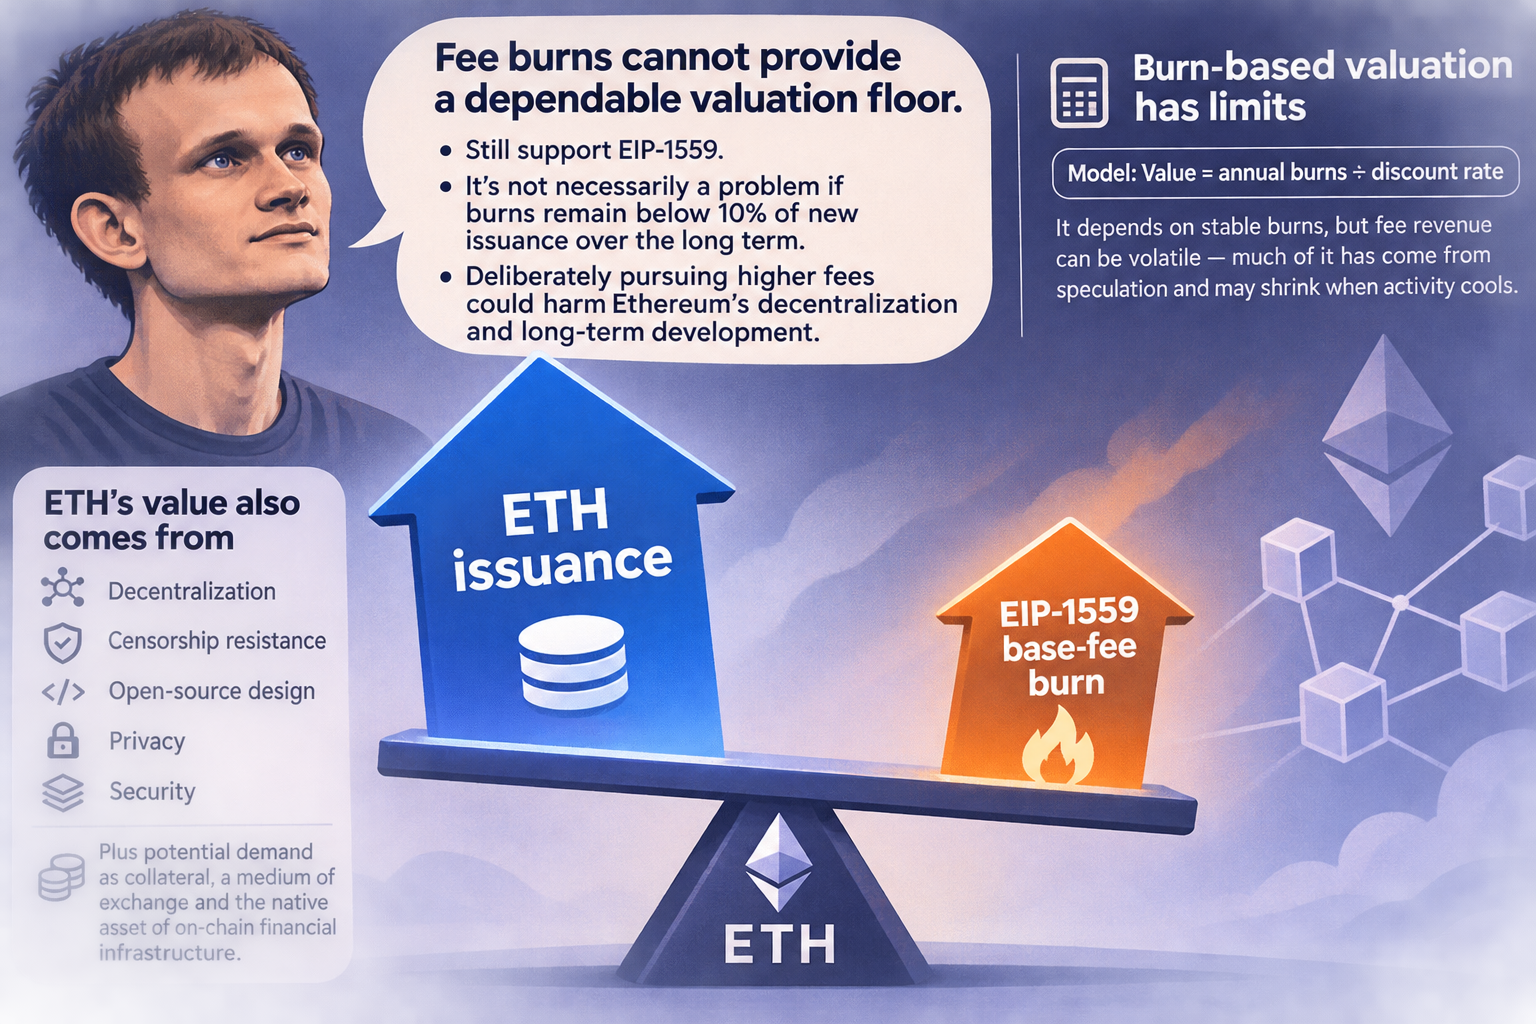
On November 8, 2026, Vitalik Buterin revisited the case for valuing ETH through transaction-fee burns. His concern, as reported by Odaily, was that burns cannot provide a dependable valuation floor: much of the fee revenue behind earlier burns came from speculation within crypto markets and could shrink when activity cooled. Odaily published its analysis on November 11, 2026, at 20:30 UTC+8.
Buterin still supported retaining EIP-1559. He argued that it would not necessarily be a problem if burns remained below 10% of new issuance over the long term. Deliberately pursuing higher fees to sustain burns, he said, could instead harm Ethereum’s decentralization and long-term development.
Issuance and burns differ across chains
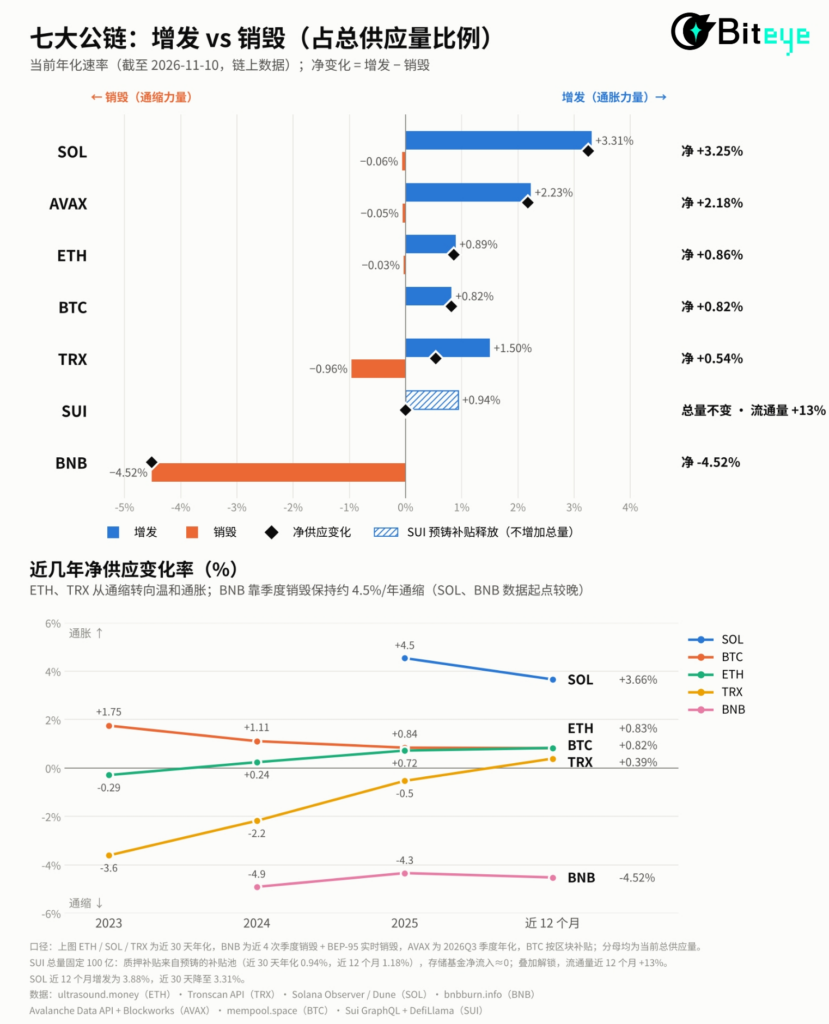
Odaily compared seven assets to show why a falling supply—or a high burn figure—cannot be assumed across public chains:
| Asset | Supply mechanism and reported figures |
|---|---|
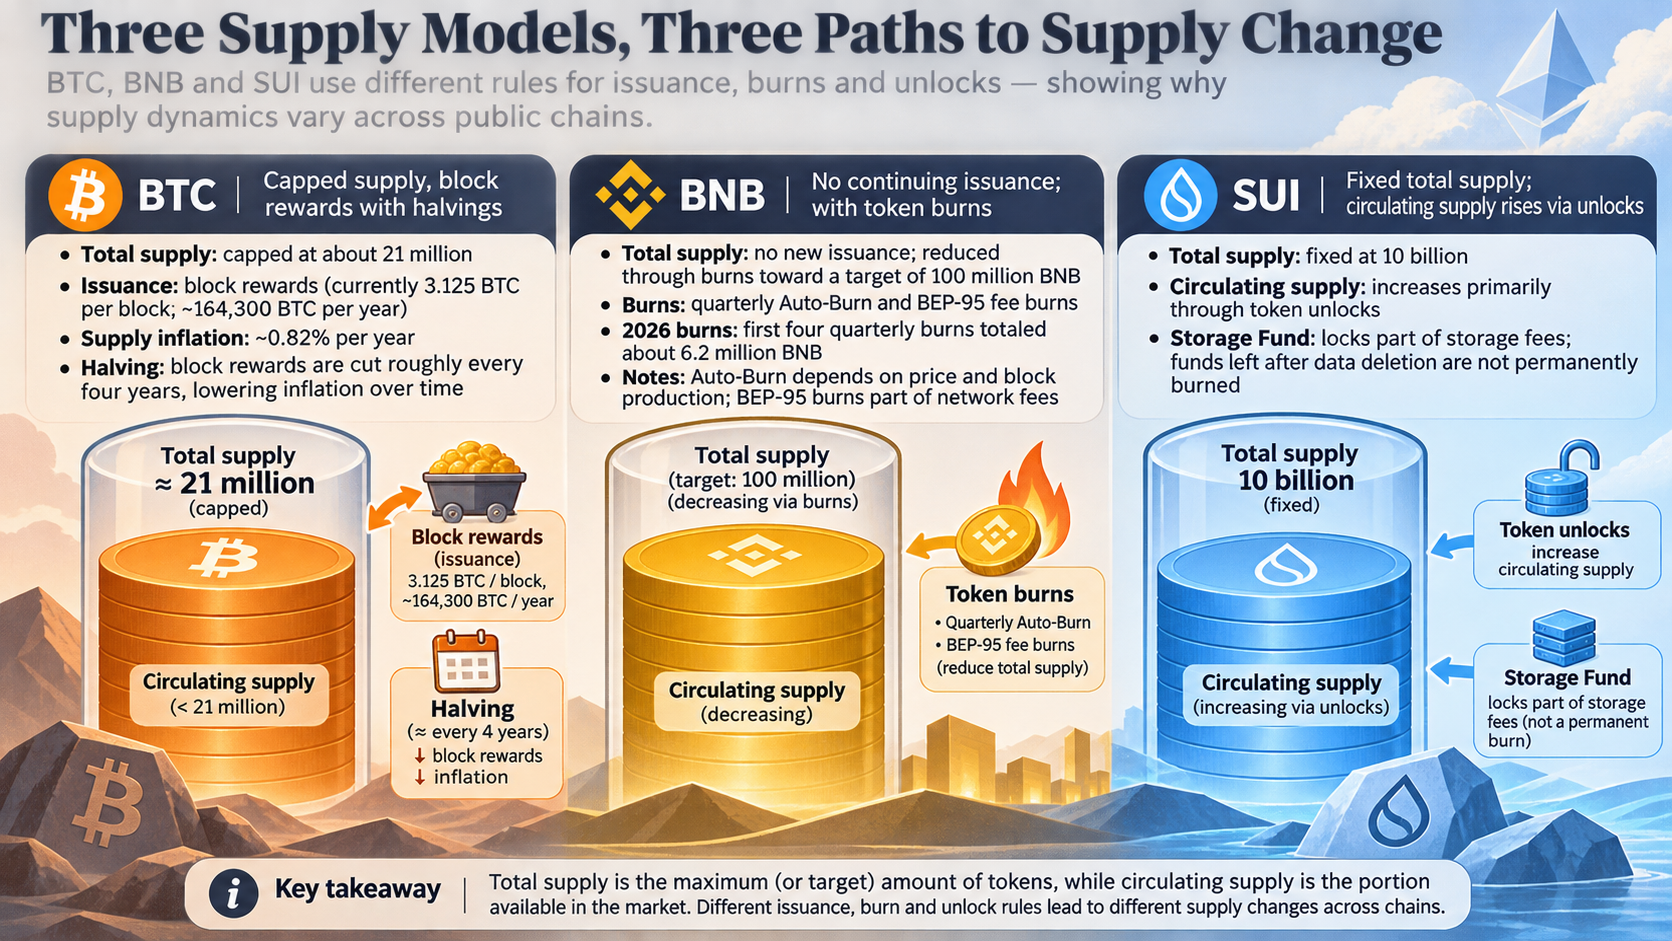
| BTC | Supply is capped at about 21 million. At a 3.125 BTC block reward and an average ten-minute block interval, Odaily estimated roughly 164,300 new BTC a year, or 0.82% annual supply inflation. |
| ETH | Supply had grown about 1.37% since the 2022 Merge. EIP-1559 burns base fees, but burns over the preceding 30 days offset only about 3.2% of new issuance, according to Odaily. |
| SOL | Its initial annual inflation rate was 8%, designed to decline by 15% each year toward a long-term target of 1.5%. Daily burns exceeded 10,000 SOL at one point during the 2024 meme-coin boom; in January 2025, burns offset about 23% of issuance. After SIMD-0096 directed all priority fees to validators while retaining a burn of 50% of base fees, daily burns fell to around 700 SOL at one point. |
| BNB | It has no continuing issuance. Quarterly Auto-Burn and BEP-95 fee burns reduce supply toward a target of 100 million BNB. Odaily reported that the first four quarterly burns of 2026 totaled about 6.2 million BNB. Auto-Burn depends on price and block production; BEP-95 burns part of network fees. |
| TRX | Block rewards issue TRX, while fees paid for Energy and Bandwidth are burned. Users can also obtain those resources by staking or renting them, so more USDT transfers do not necessarily mean proportionally more burns. |
| AVAX | Supply is capped at 720 million. Validator rewards add supply, while fees on the main network’s X, C and P chains are burned. As of early November 2026, Odaily reported about 474 million AVAX minted, including roughly 114 million in staking rewards, against about 5.18 million burned. |
| SUI | Total supply is fixed at 10 billion; circulating supply rises primarily through unlocks. Its Storage Fund locks part of storage fees, but funds left there after data deletion are not permanently burned. |
Where a burn-based valuation breaks down
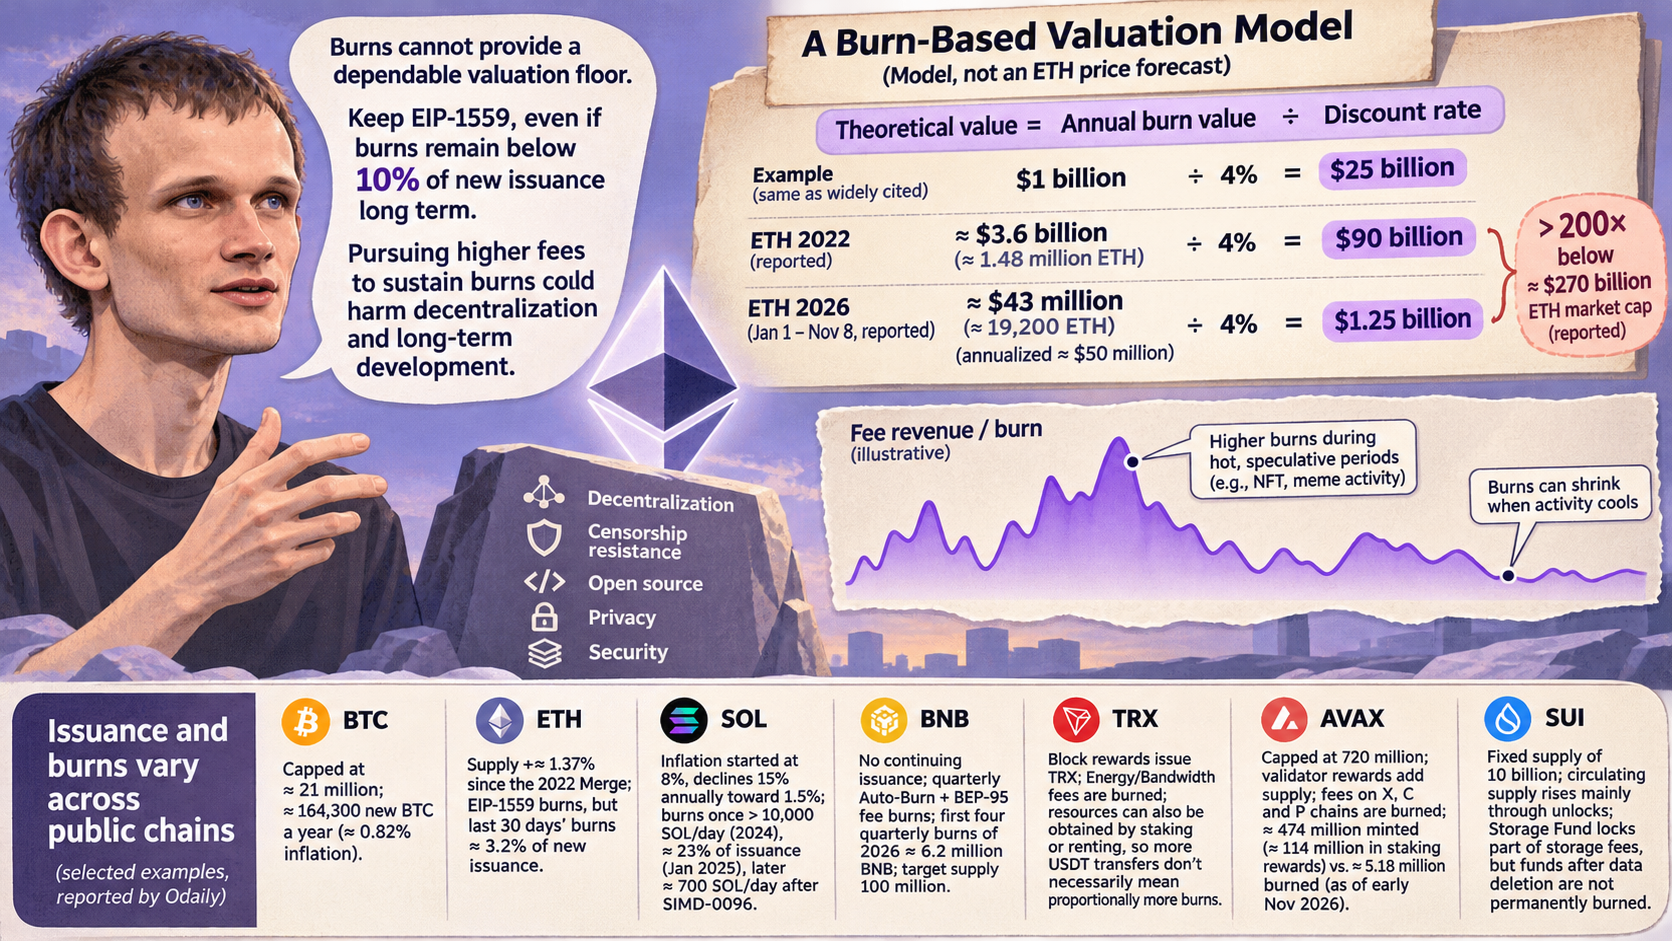
Buterin discussed a once-popular model that divides the annual value of burned tokens by a discount rate. At $1 billion in stable annual burns and a 4% rate, it produces a theoretical value of $25 billion. Its dependence on stable burns is the problem.
Odaily reported that Ethereum burned about 1.48 million ETH, worth roughly $3.6 billion, in 2022. From the start of 2026 through November 8, it reported burns of only about 19,200 ETH, worth roughly $43 million. Annualizing that latter dollar figure to approximately $50 million and applying the same 4% rate yields $1.25 billion—more than 200 times below the roughly $270 billion ETH market capitalization Odaily cited at the time. That gap illustrates the model’s limits; it is not a price target.
Burns also omit some ways network activity is distributed economically. Odaily pointed to Solana priority fees paid to validators and TRON resource rentals that may benefit stakers. Meanwhile, fee revenue tied to speculative activity may not persist from one market cycle to the next.
Buterin placed greater weight on Ethereum’s decentralization, censorship resistance, open-source design, privacy and security. Odaily also raised the possibility of demand for ETH as collateral, a medium of exchange and the native asset of on-chain financial infrastructure—while noting the harder question of how to value any resulting monetary premium. Unlike BTC, ETH has no fixed supply cap, and its issuance rules can change through protocol upgrades. The November 2026 debate therefore identified a limit of burn-based valuation, not a confirmed replacement for it.
Source: odaily.news (originally published 2026-11-11 20:30 UTC+8)